Know Every Customer, Counterparty and Claimant

Screen for sanctions, PEP, adverse media and ownership risk. Then keep checking, every day.
How banks and insurers can tighten screening and monitoring

Banks, exchange houses and insurers screen more people and companies than almost anyone, and the pressure keeps growing. Onboard a customer, sign a counterparty or pay a claim without knowing who’s really behind it, and their risk becomes yours. The better habit is to keep checking. Run every customer, counterparty, claimant and partner against sanctions, PEP and adverse media before you deal with them, and keep watching afterwards. That’s what Beady does. We screen properly at onboarding and then check your whole book every day, so a new sanction, charge or scandal reaches you when it happens. Since the UAE came off the FATF grey list in 2024, supervisors have kept up the pressure, not eased it.
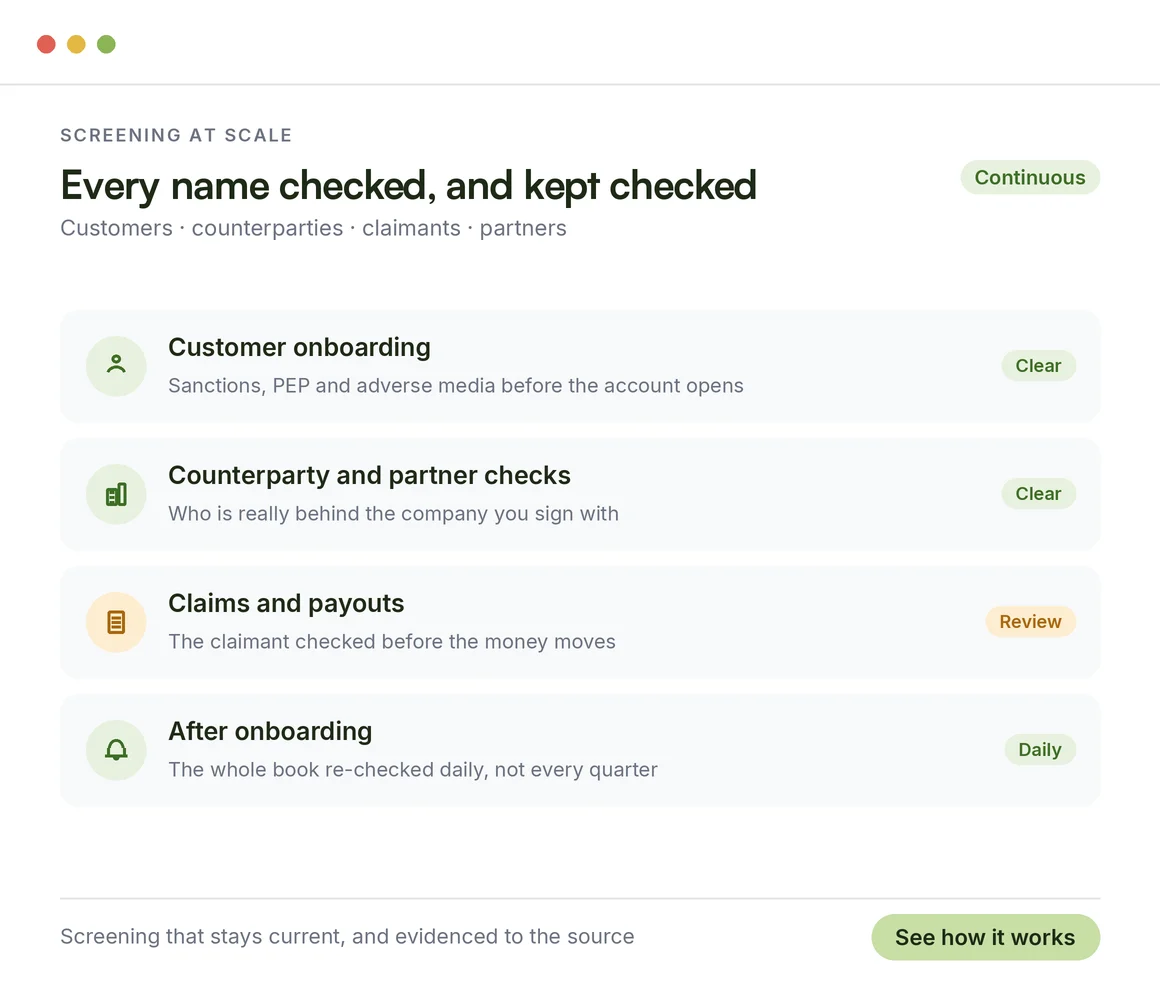
Every customer and counterparty screened at onboarding and re-checked daily
Why older screening tools let finance and insurance down

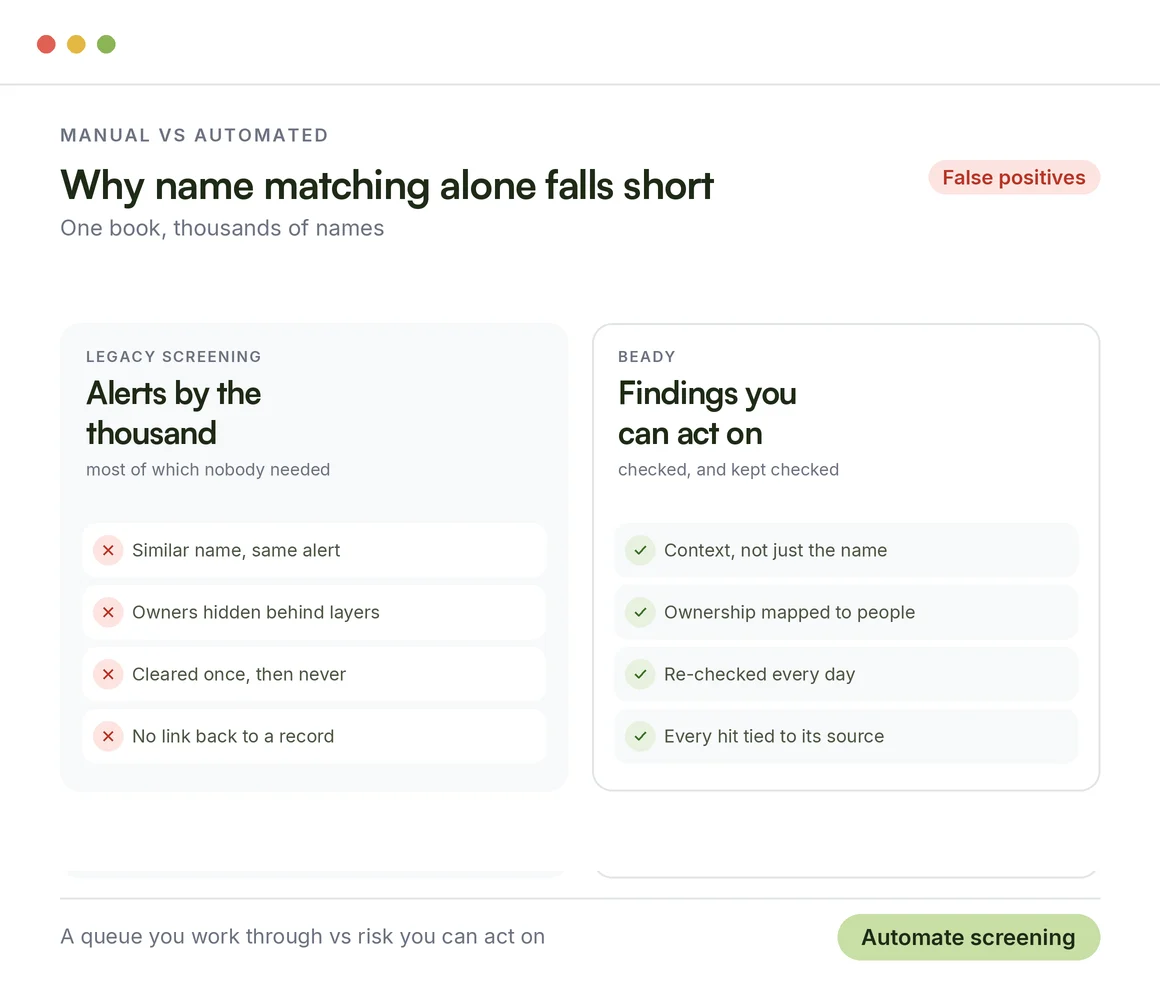
Older screening tools were built to match names, not to judge risk, and it shows. They flag everyone with a similar name and bury compliance teams in false positives. In the UAE, where a single common name can match hundreds of customers, that gets out of hand fast. Meanwhile the real risks get lost in the noise. Ownership is another blind spot. The people behind a corporate customer or counterparty are often hidden under layers a name check never untangles. And most screening is a one-off gate. You approve a customer at onboarding and look again on a fixed cycle, so a new sanction, charge or scandal in between goes unnoticed until an inspector, or a newspaper, finds it first.

Legacy name matching versus Beady: alerts by the thousand against findings you can act on
Why you need checks at onboarding and afterwards

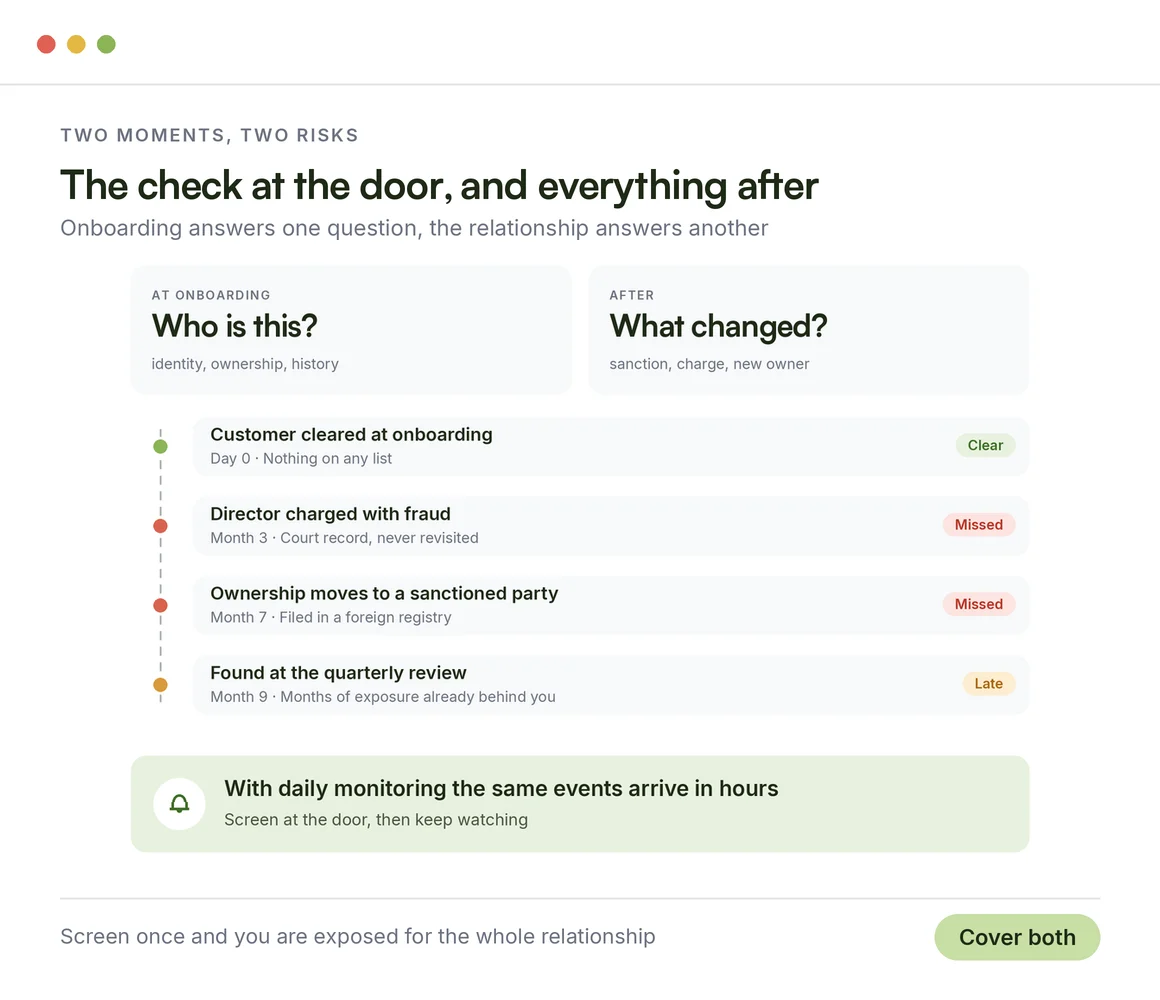
UAE supervisors, from the CBUAE to the DFSA and the FSRA, increasingly expect both. At onboarding, you want to know whether a customer, counterparty or claimant is who they say they are, and whether anything in their past should stop you. Later, the question is what’s changed. A new sanction? A fraud charge? A scandal? A new owner? Check only at onboarding and you’re exposed for the rest of the relationship. Check only now and then and you’re always behind. Beady does both: a proper check at the start and daily monitoring after.

Why onboarding screening and ongoing monitoring both matter: a timeline of what changes after the check
What one missed risk costs a financial institution

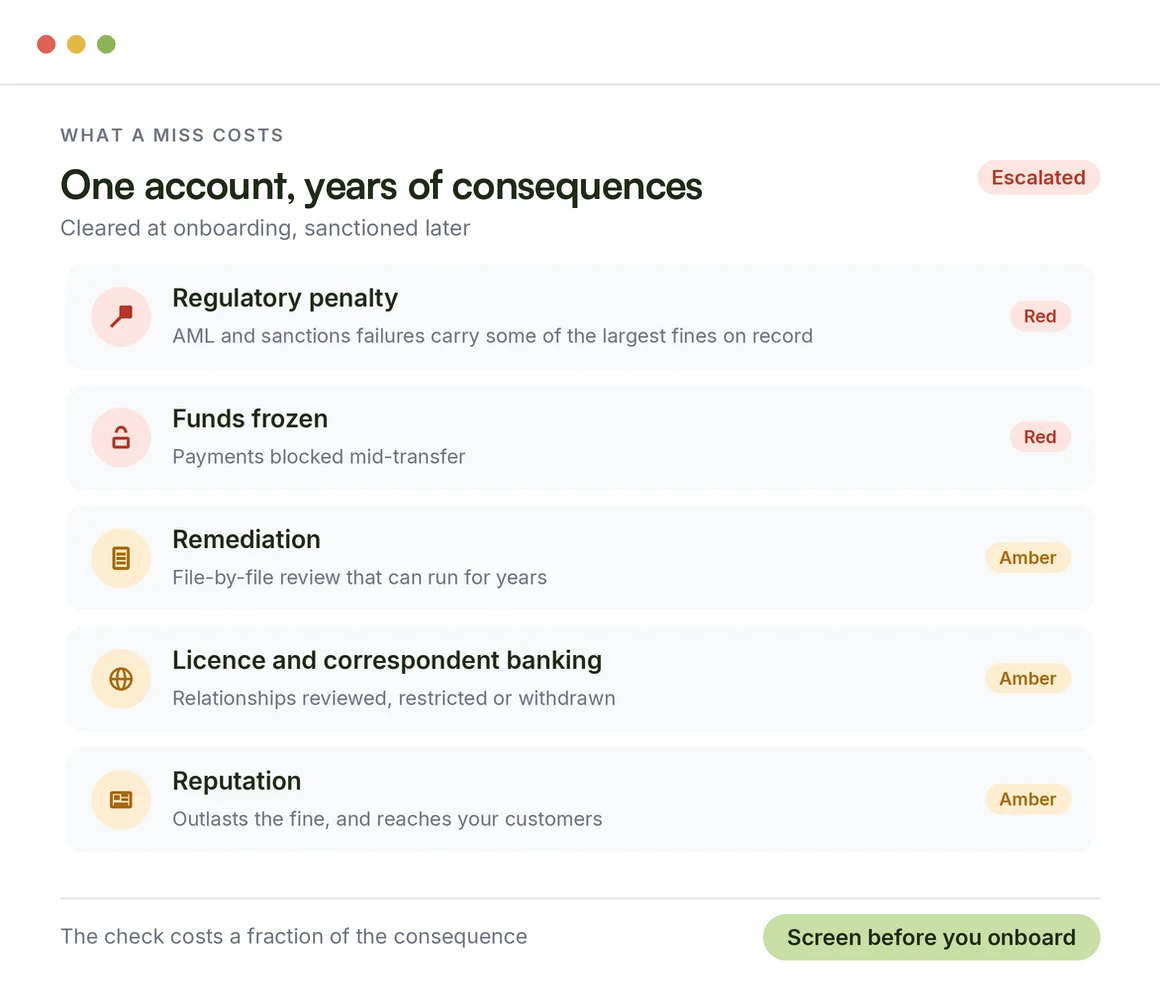
In financial services, one missed risk can cost much more than one account. Onboard or pay a sanctioned party and you may be breaking the law. Regulators like OFAC and FinCEN have handed out some of the biggest fines on record for AML and sanctions failures, and the CBUAE regularly fines banks, exchange houses and insurers here too. Funds can be frozen, clean-up work can drag on for years, and a serious failure can put your licence and your correspondent banking relationships at risk. The damage to your reputation often lasts longer than the fine. Most of this is avoidable with proper screening. Beady checks every customer, counterparty and claimant against sanctions and adverse media before you’re exposed, and keeps watching after that.

What one missed risk costs a financial institution: fines, frozen funds, remediation, licence and reputation
How AI helps with financial crime screening

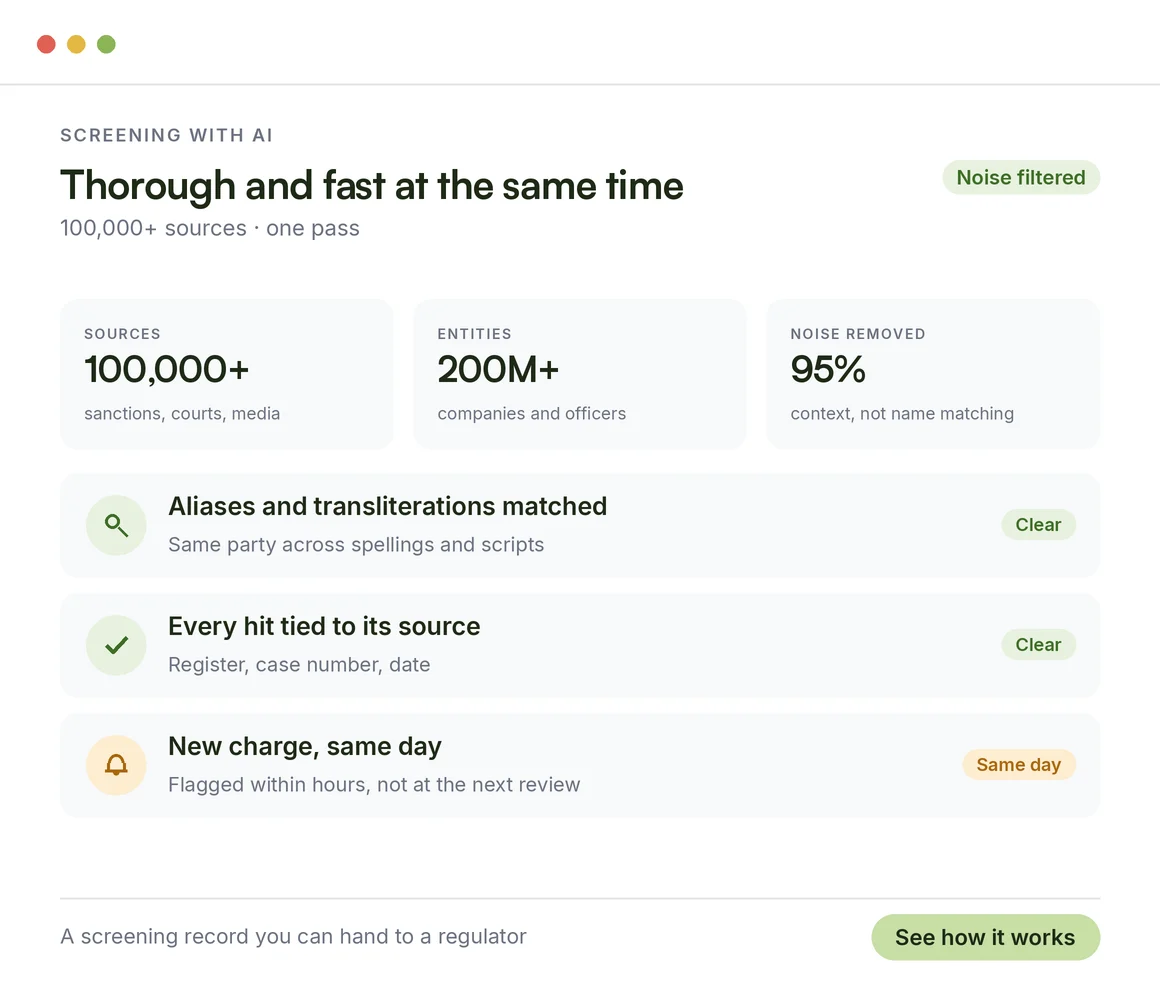
AI lets a financial institution screen at scale without drowning in false positives. Beady checks a customer, counterparty or claimant against sanctions, adverse media, litigation and more than 100,000 other sources in minutes, and maps ownership across more than 200M entities and officers. Up to 95% of the noise is filtered out, so your team looks at real risk instead of dead-end alerts. After that it checks daily and tells you within hours about a new sanction, charge or scandal. Every finding links to its source, which is what any regulator or auditor will ask for.

AI screening across 100,000+ sources with noise filtered and every hit tied to its source
01 Screen Customers and Counterparties at Onboarding
Every customer and counterparty carries risk you can’t see at face value. At onboarding, Beady checks the people and companies behind them against sanctions, PEP, criminal and adverse media sources. A high-risk party gets caught before they’re on your books, not after.
02 Screen Policyholders, Claimants, Agents and Brokers
In insurance and takaful, the risk goes well beyond your customers. Beady checks policyholders, claimants, agents and brokers against sanctions, adverse media and fraud signals. A sanctioned party, a fraudulent claimant or a dodgy intermediary gets spotted before they cost you a payout or a penalty.
03 Map Ownership and Uncover UBOs and Hidden Connections
You can’t judge a corporate customer’s risk until you know who controls it. Beady maps beneficial ownership across more than 200 million entities and officers and brings out the UBOs, related parties and hidden links. An opaque structure can’t hide a sanctioned or high-risk party behind a company that looks perfectly fine.
04 Catch Fraud, Financial Crime and Integrity Red Flags
Fraud and financial crime usually leave a public trail before they reach you. Beady checks customers, counterparties and claimants for arrests, indictments, lawsuits and bad press. Better to find a financial crime risk in screening than on your balance sheet.
05 Screen Against Sanctions and PEP Exposure
Sanctions are among the highest-stakes obligations in finance, and breaches are punished hard. Beady screens everyone against the UAE Local Terrorist List, the UN, OFAC, the EU and the UK’s HMT, plus PEP data, all refreshed daily. A newly sanctioned or politically exposed party is caught before you transact, and in the UAE, where you’re expected to freeze funds without delay, that timing matters.
06 Monitor Customers and Counterparties Continuously
Regulators increasingly expect ongoing KYC, not a one-off check. Beady checks every customer and counterparty daily, so a new sanction, charge or scandal reaches you within hours instead of at your next periodic review. That gives you room to act before it becomes a real problem.
07 Meet AML, KYC, KYB and Regulatory Obligations
Financial institutions face some of the strictest compliance rules anywhere, and they have to prove they meet them. Whether you answer to the CBUAE, the DFSA, the FSRA, the SCA or VARA, Beady runs the sanctions, PEP, adverse media and ownership checks your AML, KYC and KYB obligations require and keeps the evidence with sources attached. When someone asks for proof, you have it.
08 Protect Your Licence, Banking Relationships and Reputation
A serious compliance failure can cost you a licence, a correspondent bank or years of trust. Beady helps protect all three by screening and monitoring the people and companies you deal with, so one sanctioned or fraudulent party doesn’t put your standing, your relationships or your reputation on the line.
Where Beady Fits in Your Workflow

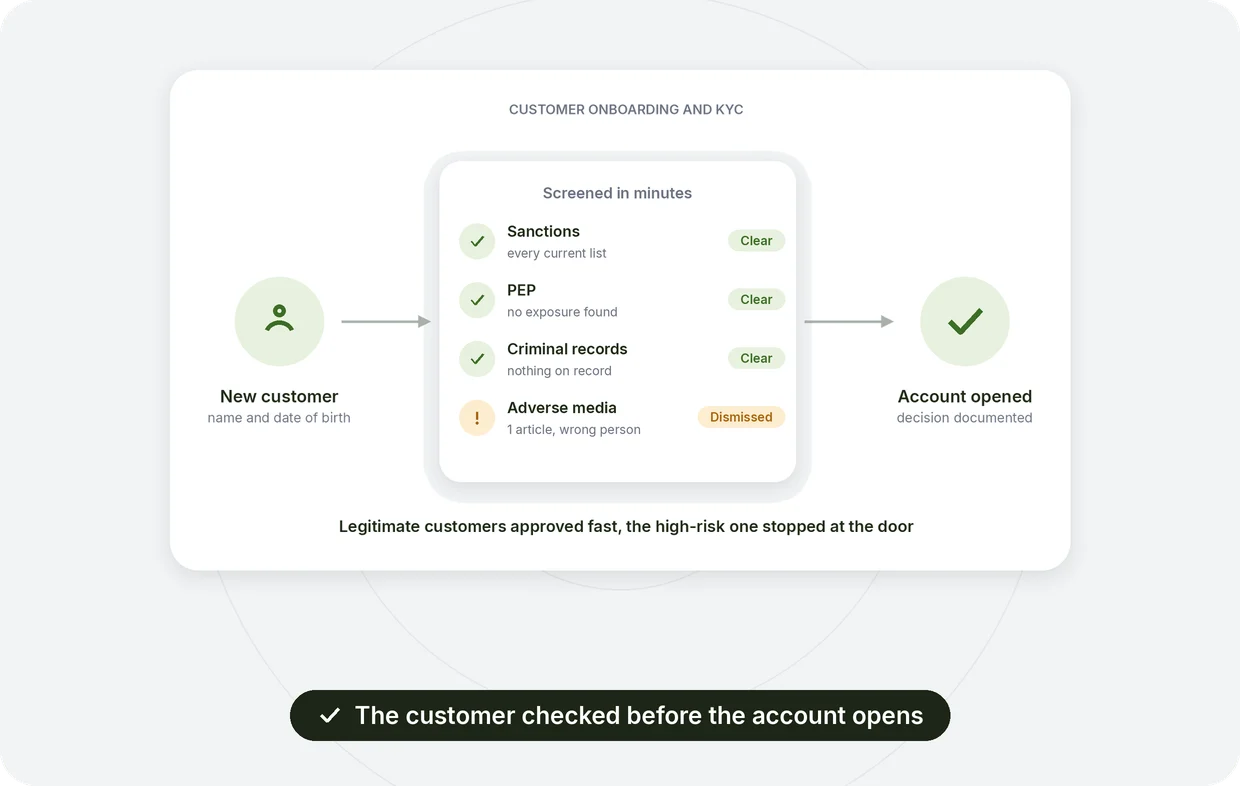
Customer onboarding and KYC: identity, sanctions and PEP checked before the account opens
Customer Onboarding and KYC
Screen every customer as they onboard. Beady checks the person behind an account against sanctions, PEP, criminal and adverse media sources in minutes. Legitimate customers get approved quickly, and sanctioned or high-risk people are stopped before they’re on your books. Your Emirates ID and UAE PASS checks stay part of your process.
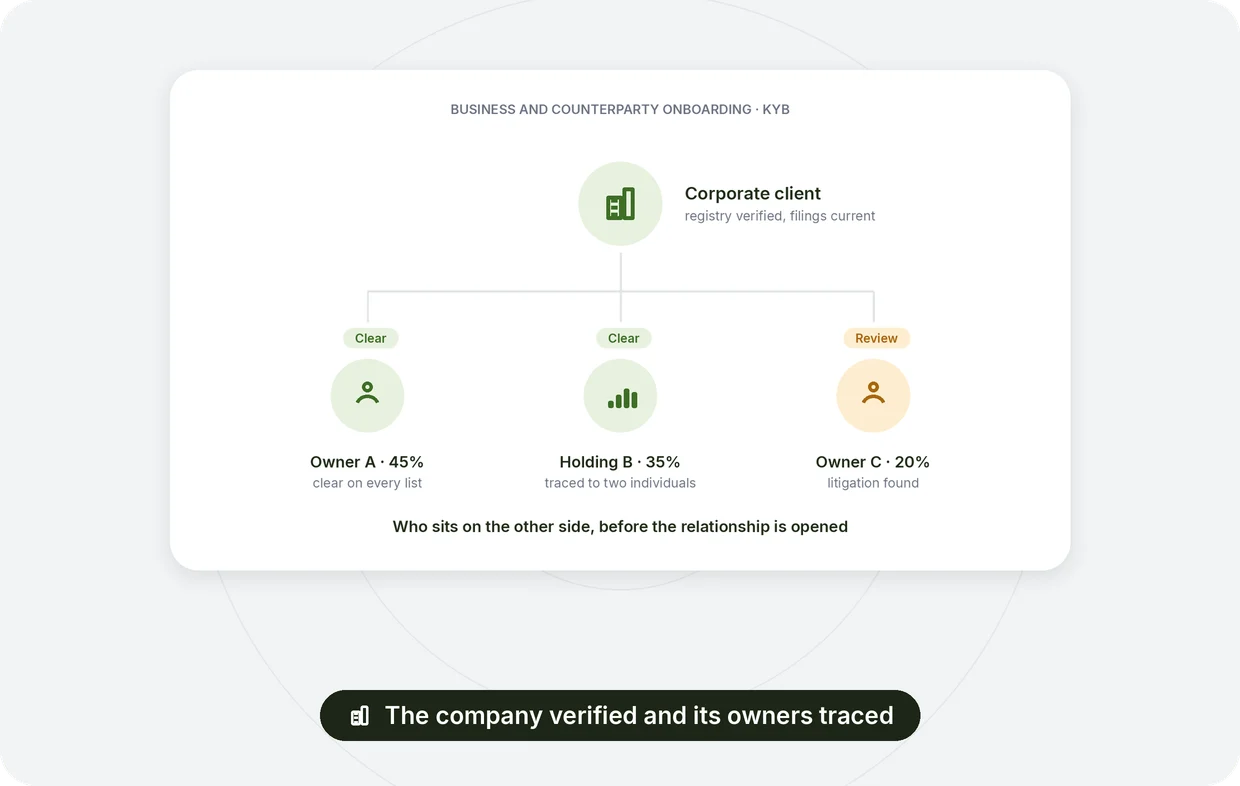
Business and counterparty onboarding: company verified and beneficial owners traced and screened
Business and Counterparty Onboarding
Taking on a corporate client, a correspondent bank or a counterparty means understanding the company and the people who own it. Beady runs KYB, traces ownership and checks for sanctions, litigation and adverse media. You’ll know exactly who’s on the other side before the relationship starts.
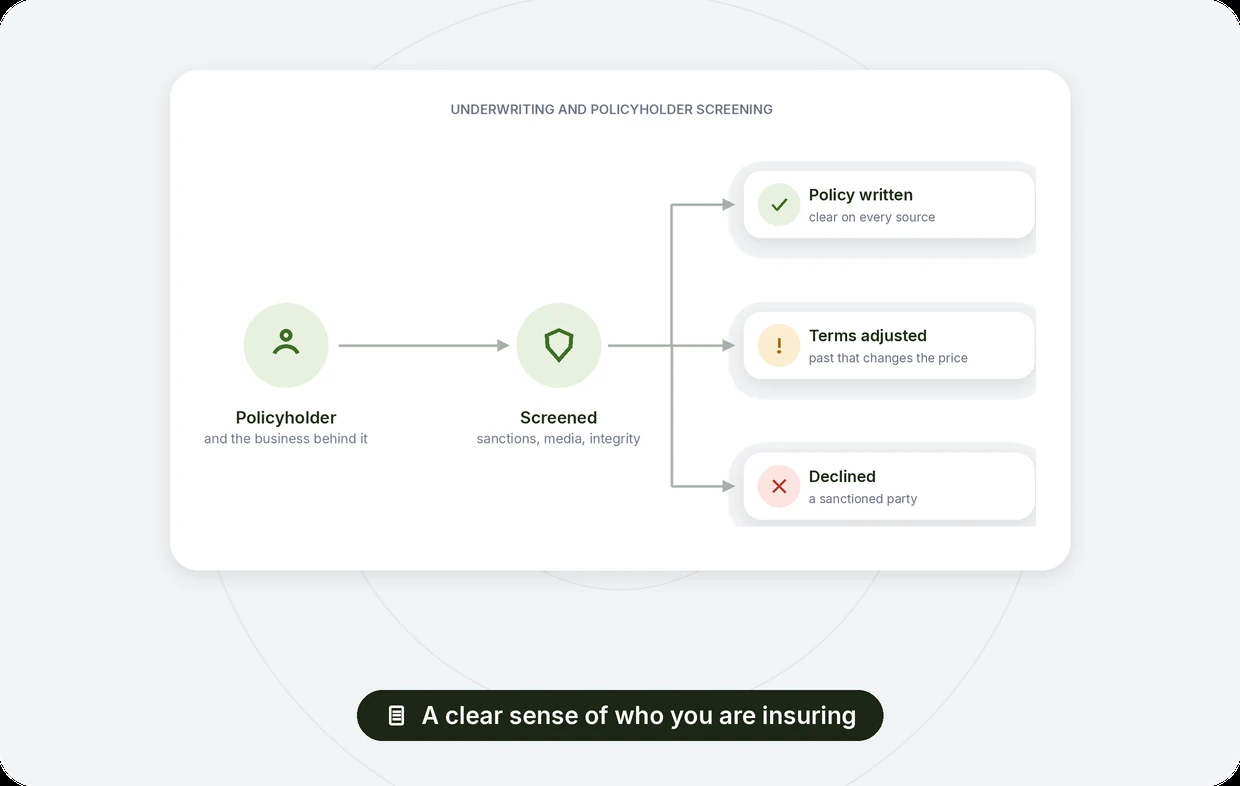
Underwriting and policyholder screening: policies auto-cleared with flagged cases sent to review
Underwriting and Policyholder Screening
Good underwriting starts with knowing who you’re insuring. Beady checks policyholders and the businesses behind them for sanctions, adverse media and integrity risk. You don’t end up writing a policy for a sanctioned party, or for a business whose history should have changed the terms, or the decision.
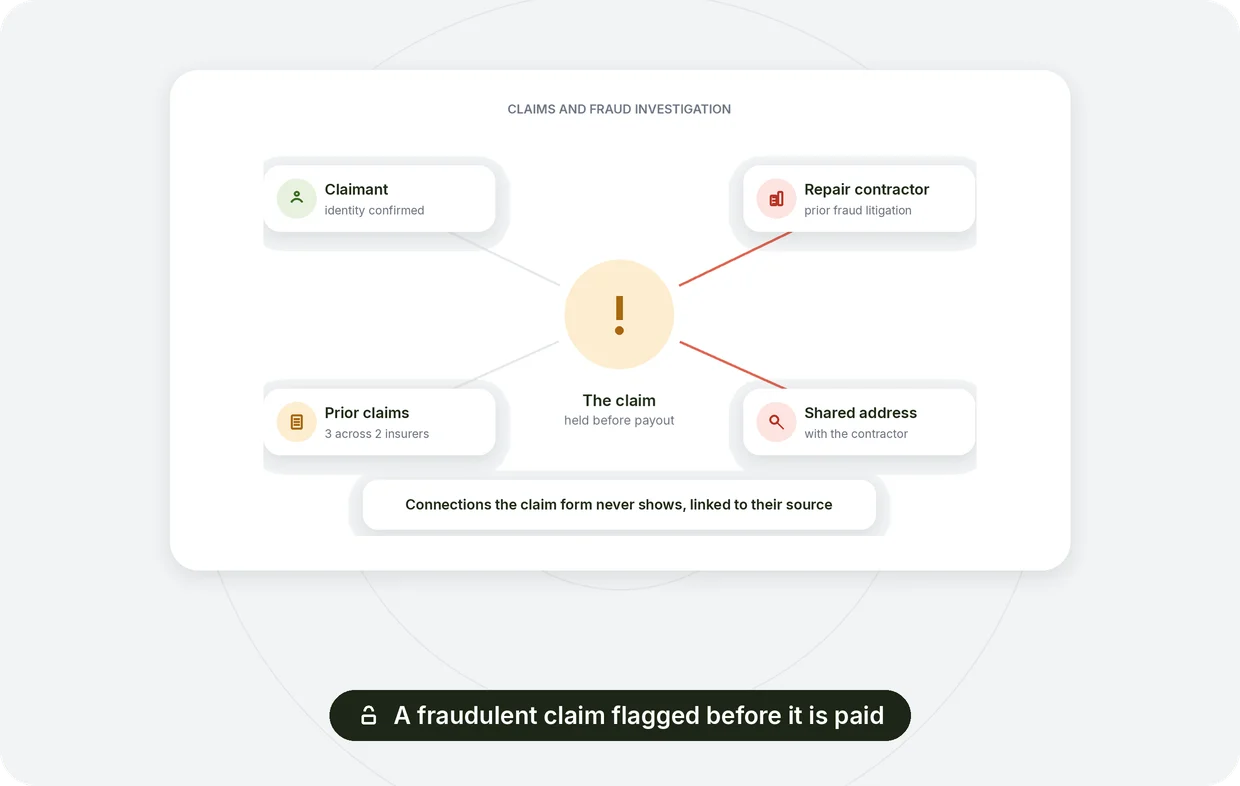
Claims and fraud investigation: the claimant, litigation and connections checked before payout
Claims and Fraud Investigation
Claims are where insurance fraud shows up. Beady gives investigators a source-linked view of a claimant and everyone around a claim, drawn from sanctions, criminal, litigation and adverse media sources. A fraudulent or high-risk claim gets flagged before it’s paid.
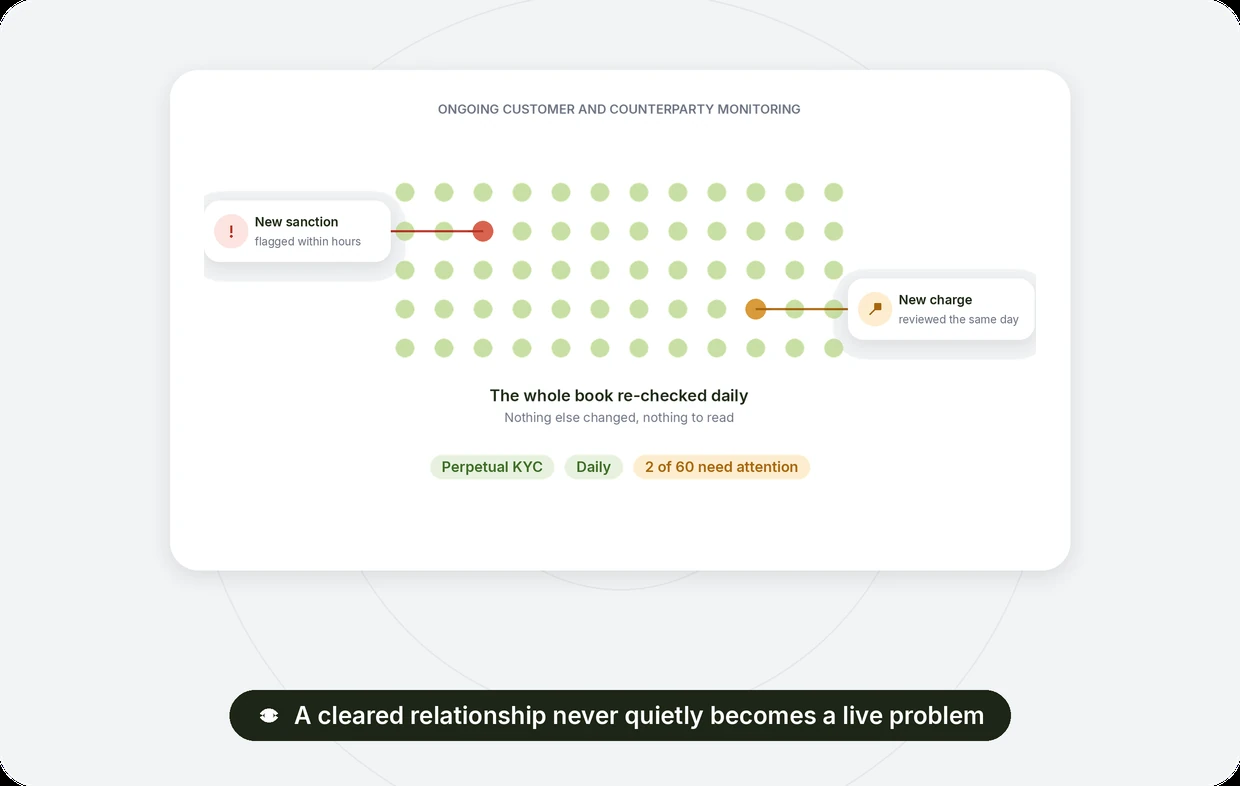
Ongoing monitoring: the whole book re-checked daily with new sanctions flagged within hours
Ongoing Customer and Counterparty Monitoring
A customer’s or counterparty’s risk changes after onboarding. Beady checks your whole book daily and flags a new sanction, charge or scandal when it happens. That supports ongoing KYC and gives you time to act before an approved relationship turns into a real problem.
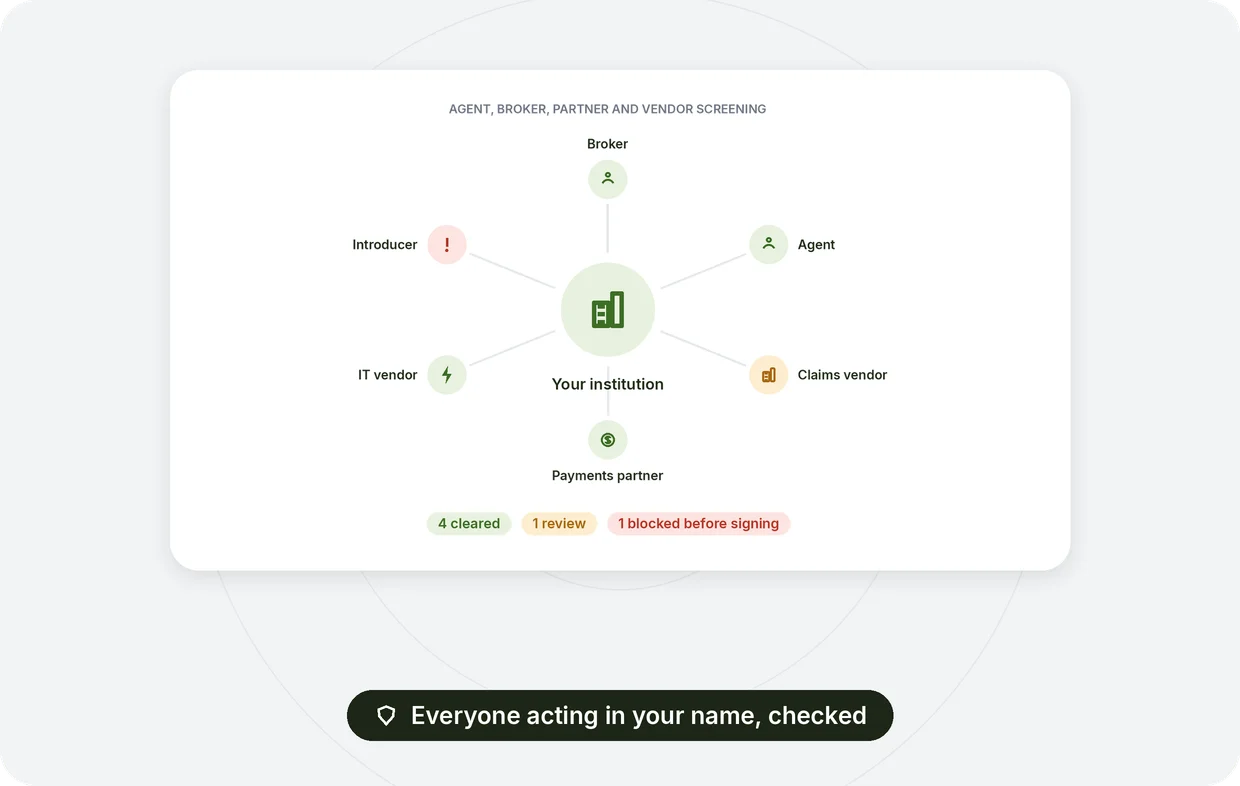
Agent, broker, partner and vendor screening: everyone acting in your name checked
Agent, Broker, Partner and Vendor Screening
Your risk extends to everyone acting on your behalf. Beady screens agents, brokers, partners and vendors, and the people behind them, for sanctions and reputational issues. A dodgy intermediary doesn’t quietly become your institution’s problem.
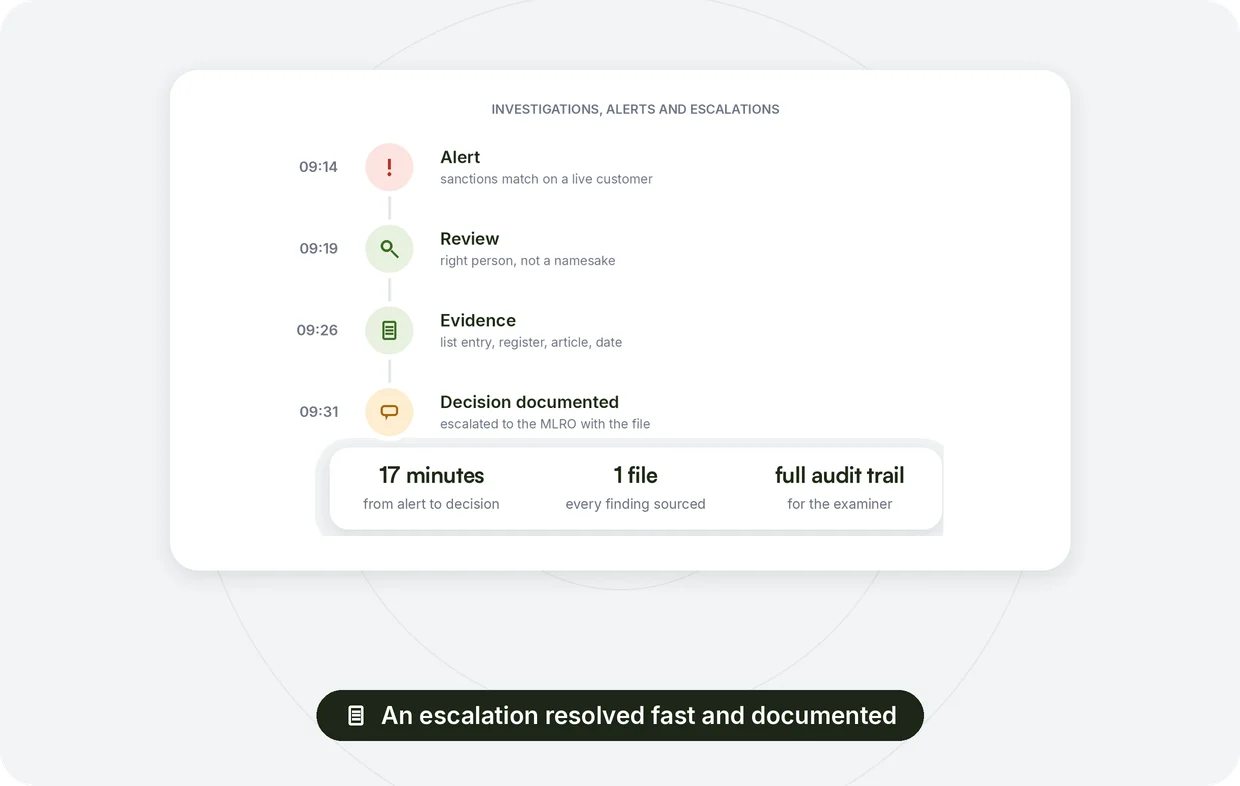
Investigations, alerts and escalations: alerts routed with evidence and a full audit trail
Investigations, Alerts and Escalations
When an alert fires or something looks off, you need answers fast. Beady gives your compliance team and MLRO a source-linked view of any customer, company or person, drawn from sanctions, criminal, litigation and adverse media sources. Escalations get resolved quickly, and the decision is documented.

The customer you approved may have changed

Checked at onboarding, then rechecked across your whole book every day.

What Beady Checks

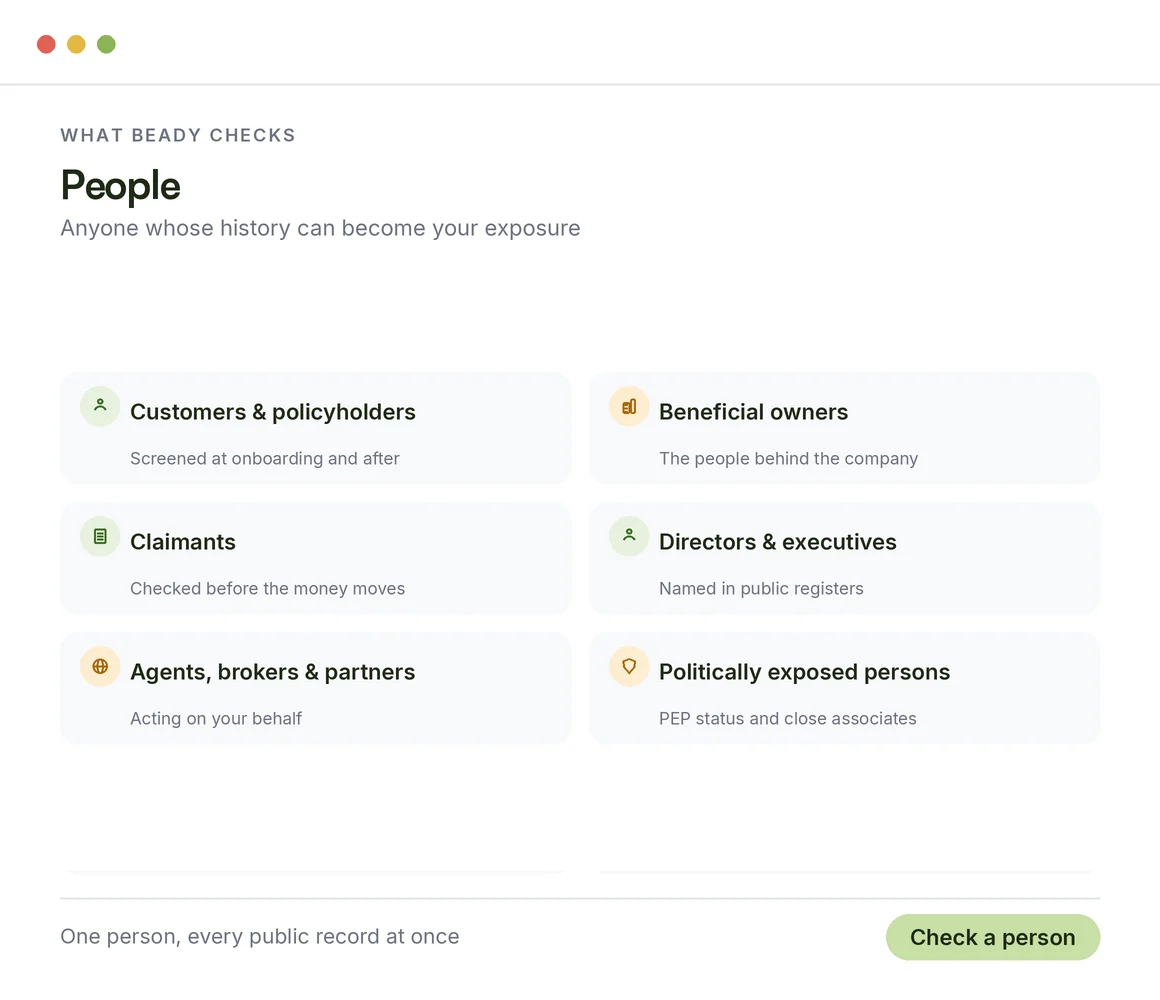
People

Follow almost any financial or insurance risk far enough and you’ll find a person. So that’s who Beady screens, and not just the names at the top. Customers. Policyholders. Claimants. The beneficial owners behind a company, the directors, the agents and brokers, and the people linked to all of them. Each one is checked against sanctions, PEP, criminal and most-wanted lists, and adverse media from more than 100,000 sources, and anyone whose political exposure raises the risk is flagged. A name on an application or a claim is only a starting point. Beady finds out who’s really behind it and what their history says, so there are no surprises about who you’ve just taken on.

People Beady checks for financial institutions: customers, beneficial owners, claimants, directors, agents and PEPs
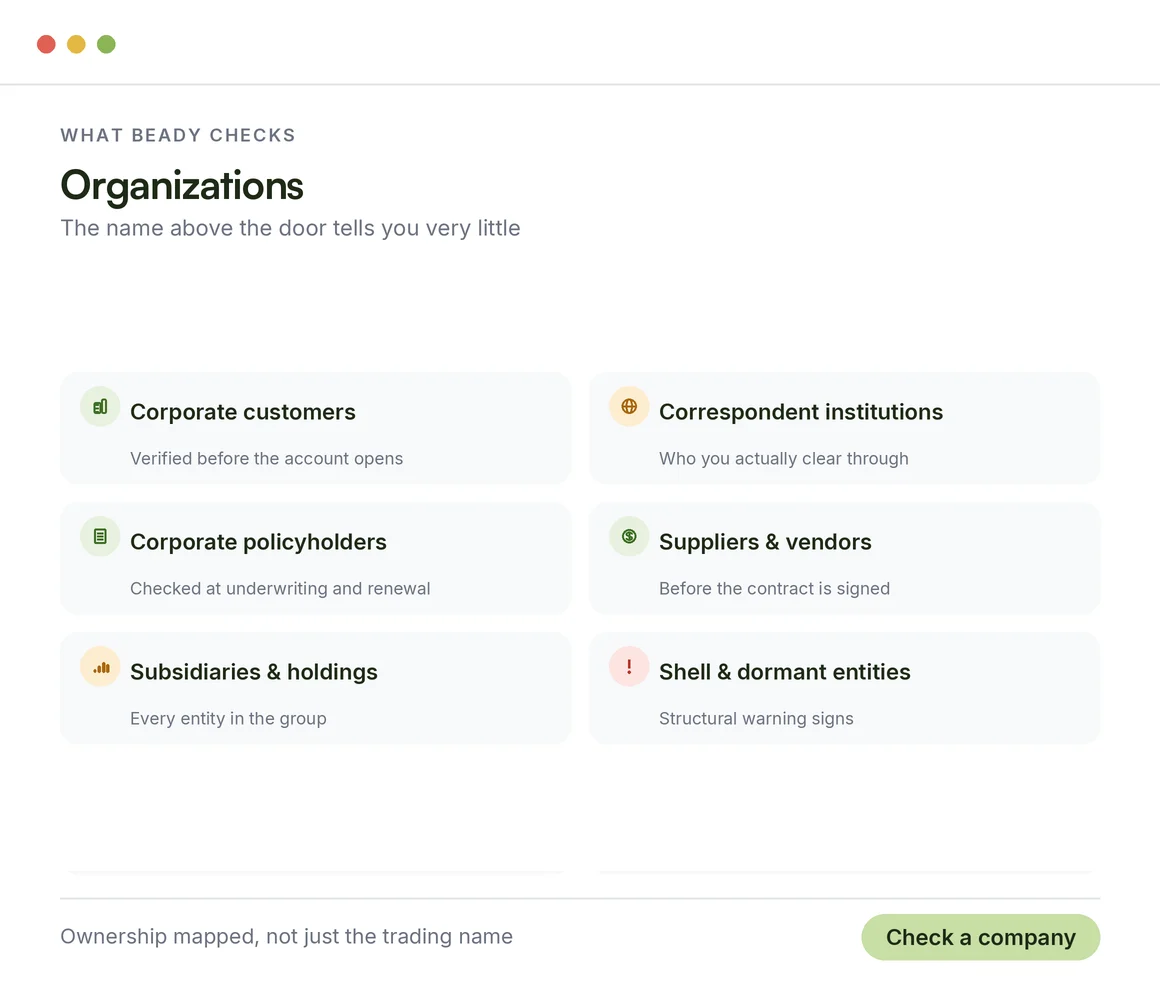
Organisations

A corporate customer’s risk is rarely obvious from the name on the account. Beady checks companies, correspondent banks, corporate policyholders and the companies around them against sanctions, litigation, adverse media and watchlists. Shell companies and opaque structures get a closer look, because they’re often set up to hide who really owns or controls a business and to move dirty money. By tracing ownership across more than 200 million legal entities and their officers, Beady helps you see the real organisation behind a name before you open a relationship or decide to keep one.

Organizations Beady checks: corporate customers, correspondent institutions, policyholders, suppliers, subsidiaries and shell entities
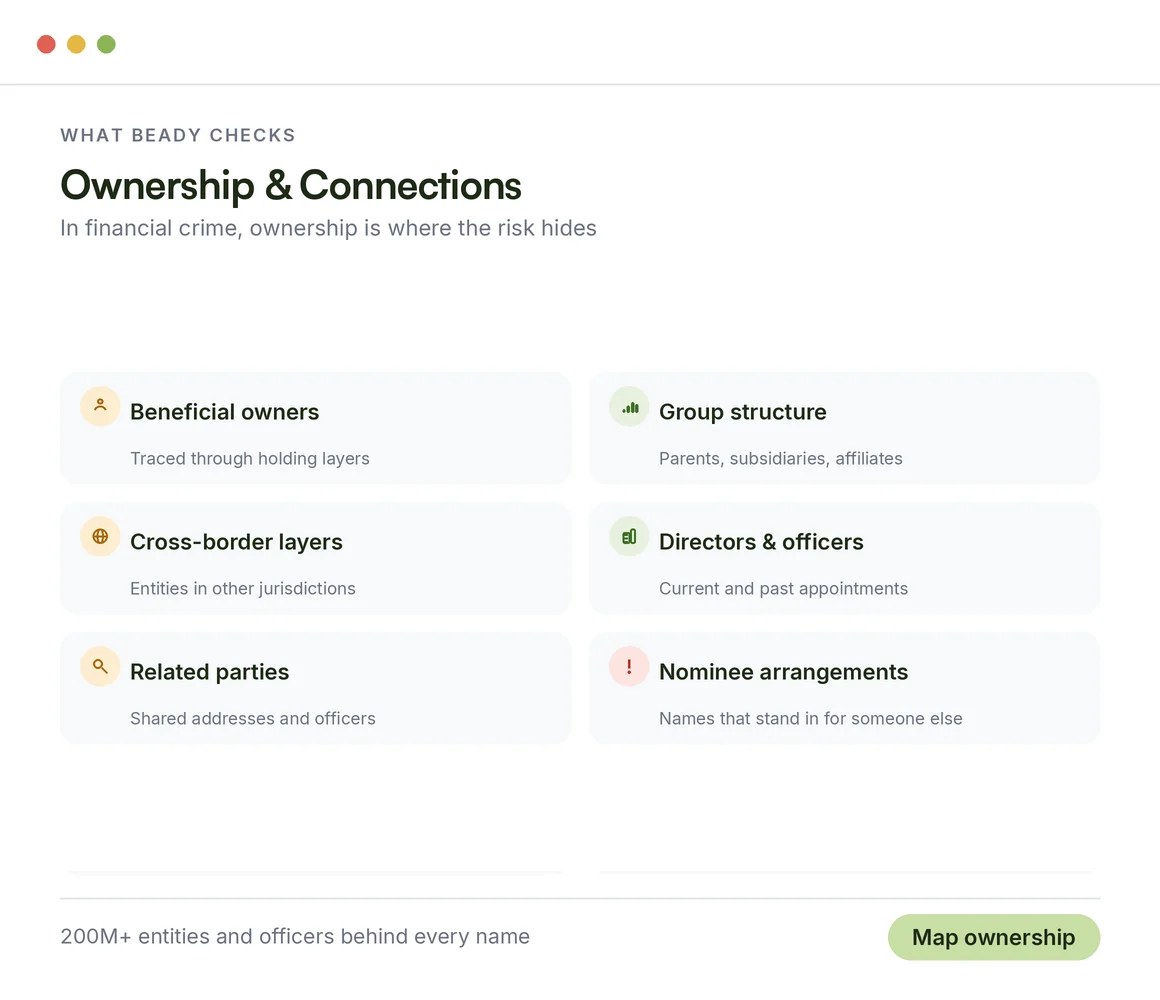
Ownership and Connections

In financial crime, ownership is often where the risk hides, and it’s exactly what regulators expect you to see. Beady maps beneficial ownership and the connections around a company using a database of more than 200 million entities and their officers, working through holding companies and intermediaries until it reaches the people who really own and control it. Along the way it brings out UBOs, related parties, conflicts and links to other people or companies you’d want to know about. You understand not just the customer in front of you, but who’s standing behind them.

Ownership and connections Beady maps: beneficial owners, group structure, cross-border layers and related parties

Built for Every Kind of Financial Institution in the UAE

From a big bank to a fast-growing fintech in DIFC or ADGM, if you take on customers and counterparties, you need to know who they are. Beady works for banks, exchange houses, insurers and fintechs of every kind.
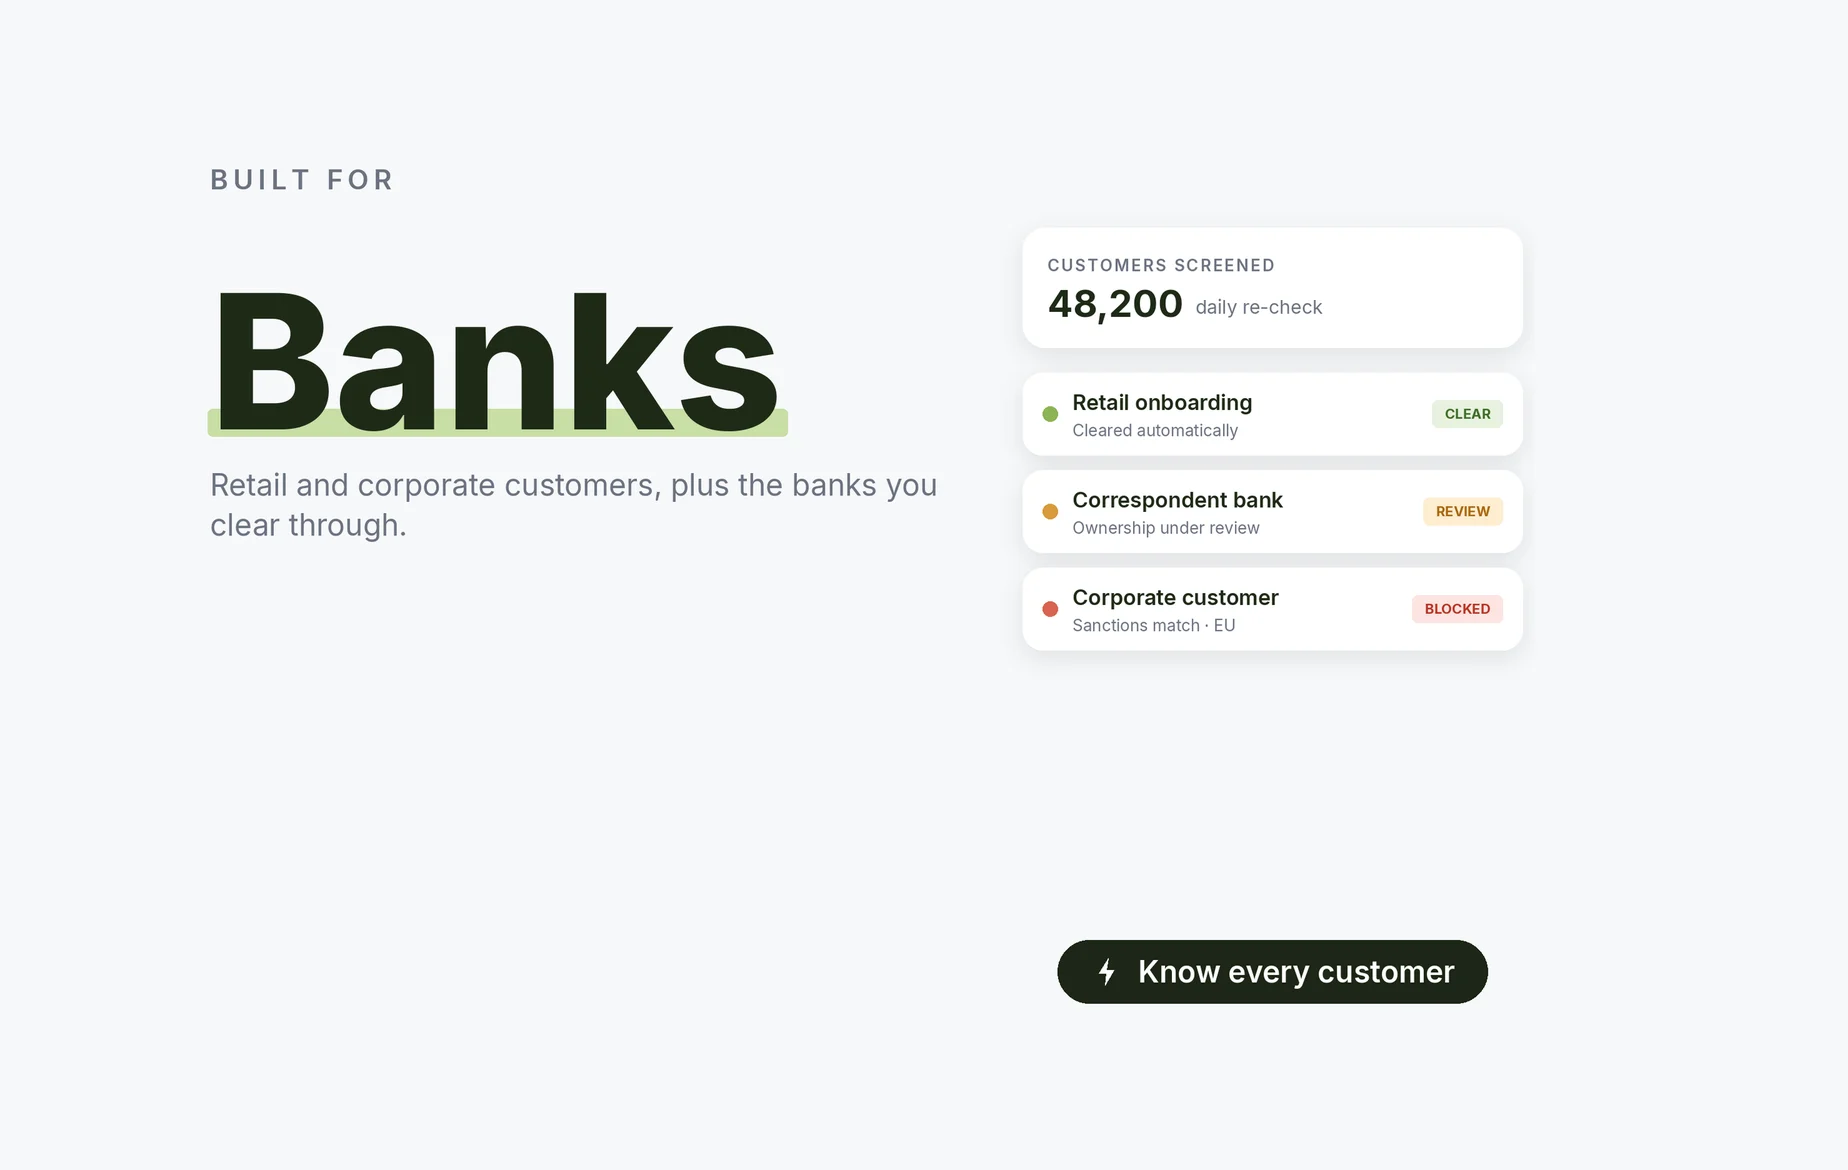
Beady for banks: retail and corporate customers and correspondent banks screened daily
For Banks
Screen every retail and corporate customer, plus correspondent banks and counterparties, for sanctions, PEP and adverse media, and keep watching them. It works the same whether you’re a conventional or Islamic bank, and it helps you meet the AML standard the CBUAE holds banks to.
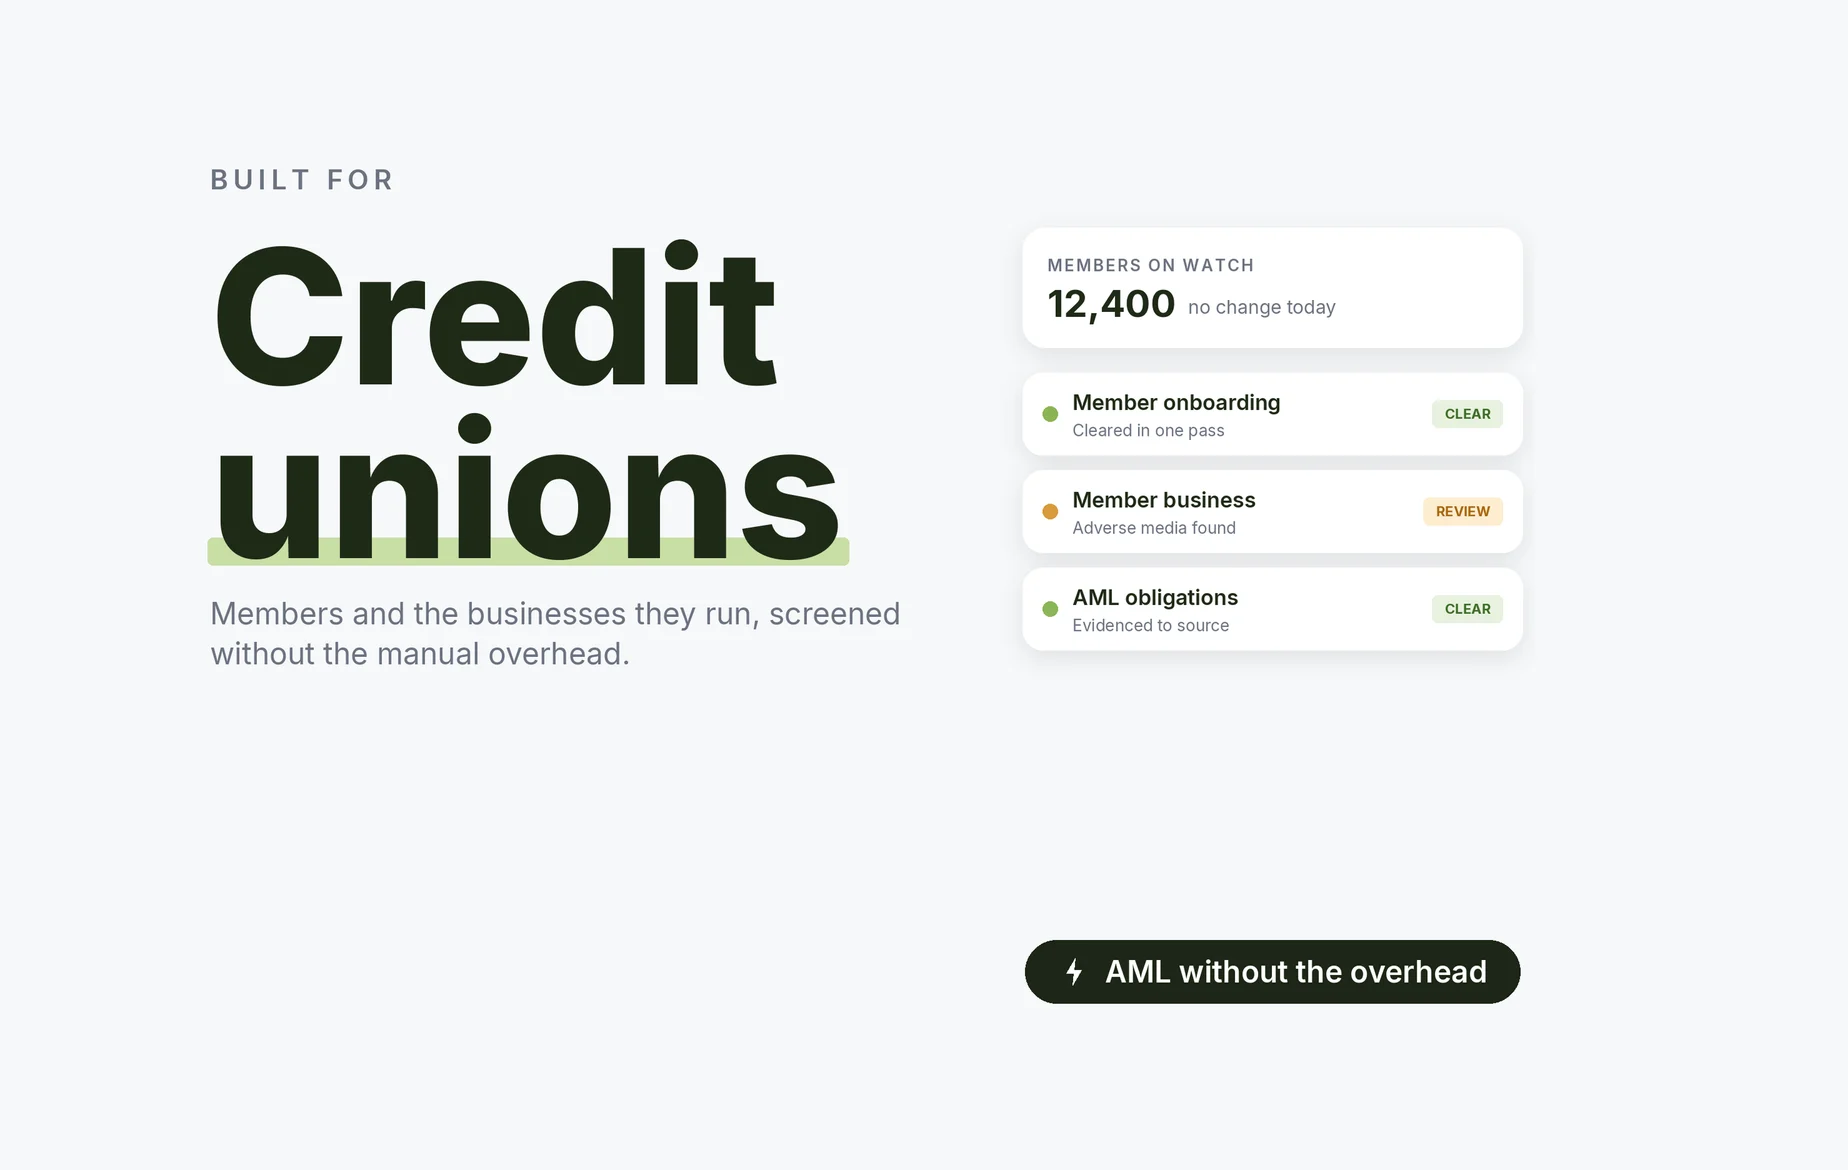
Beady for credit unions: members and their businesses screened without manual overhead
For Exchange Houses
Screen remittance customers, corporate clients and the businesses behind them for sanctions and adverse media risk. Exchange houses handle huge volumes of cross-border payments and get close attention from the CBUAE, so fast, accurate screening without a manual slog makes a real difference.
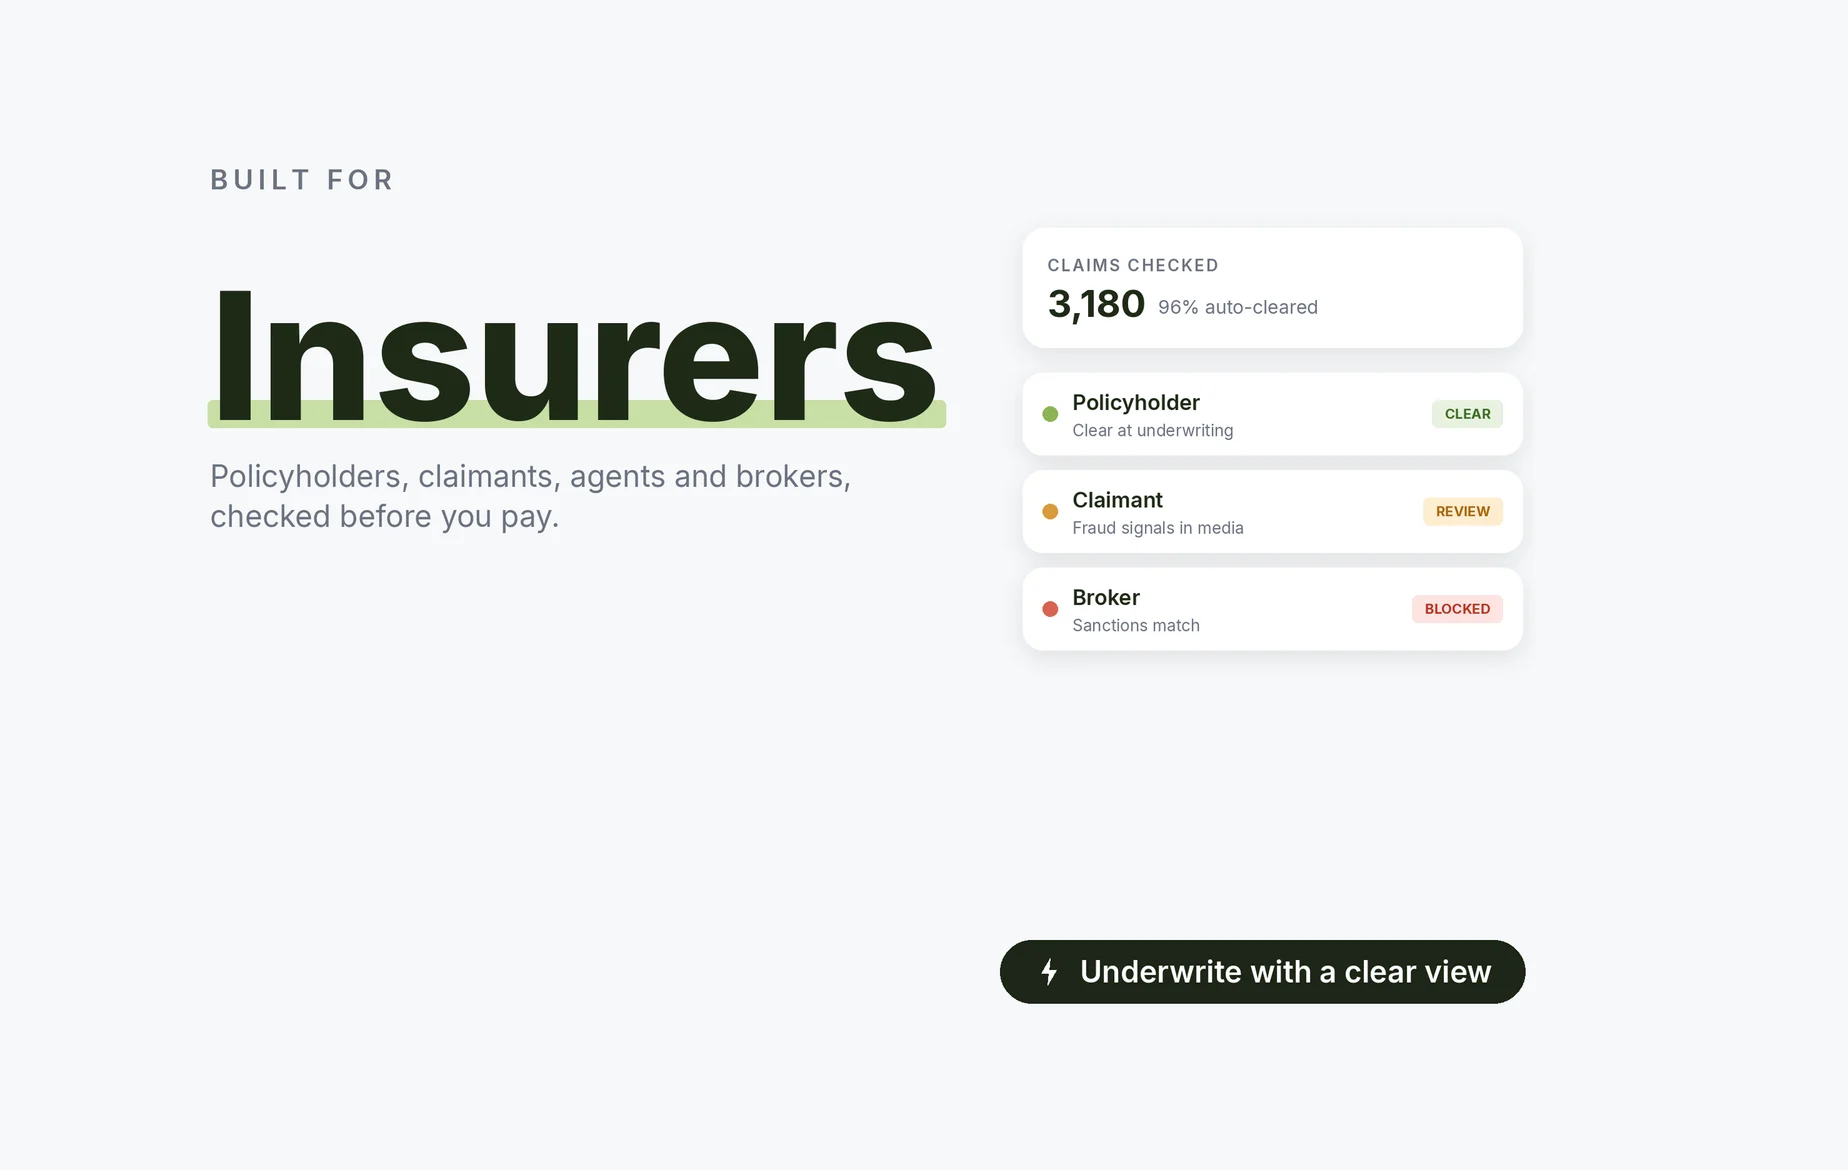
Beady for insurers: policyholders, claimants, agents and brokers checked before you pay
For Insurers and Takaful Operators
Screen policyholders, claimants, agents and brokers for sanctions, fraud and adverse media risk, so you underwrite and pay out with a clear view of who you’re dealing with.
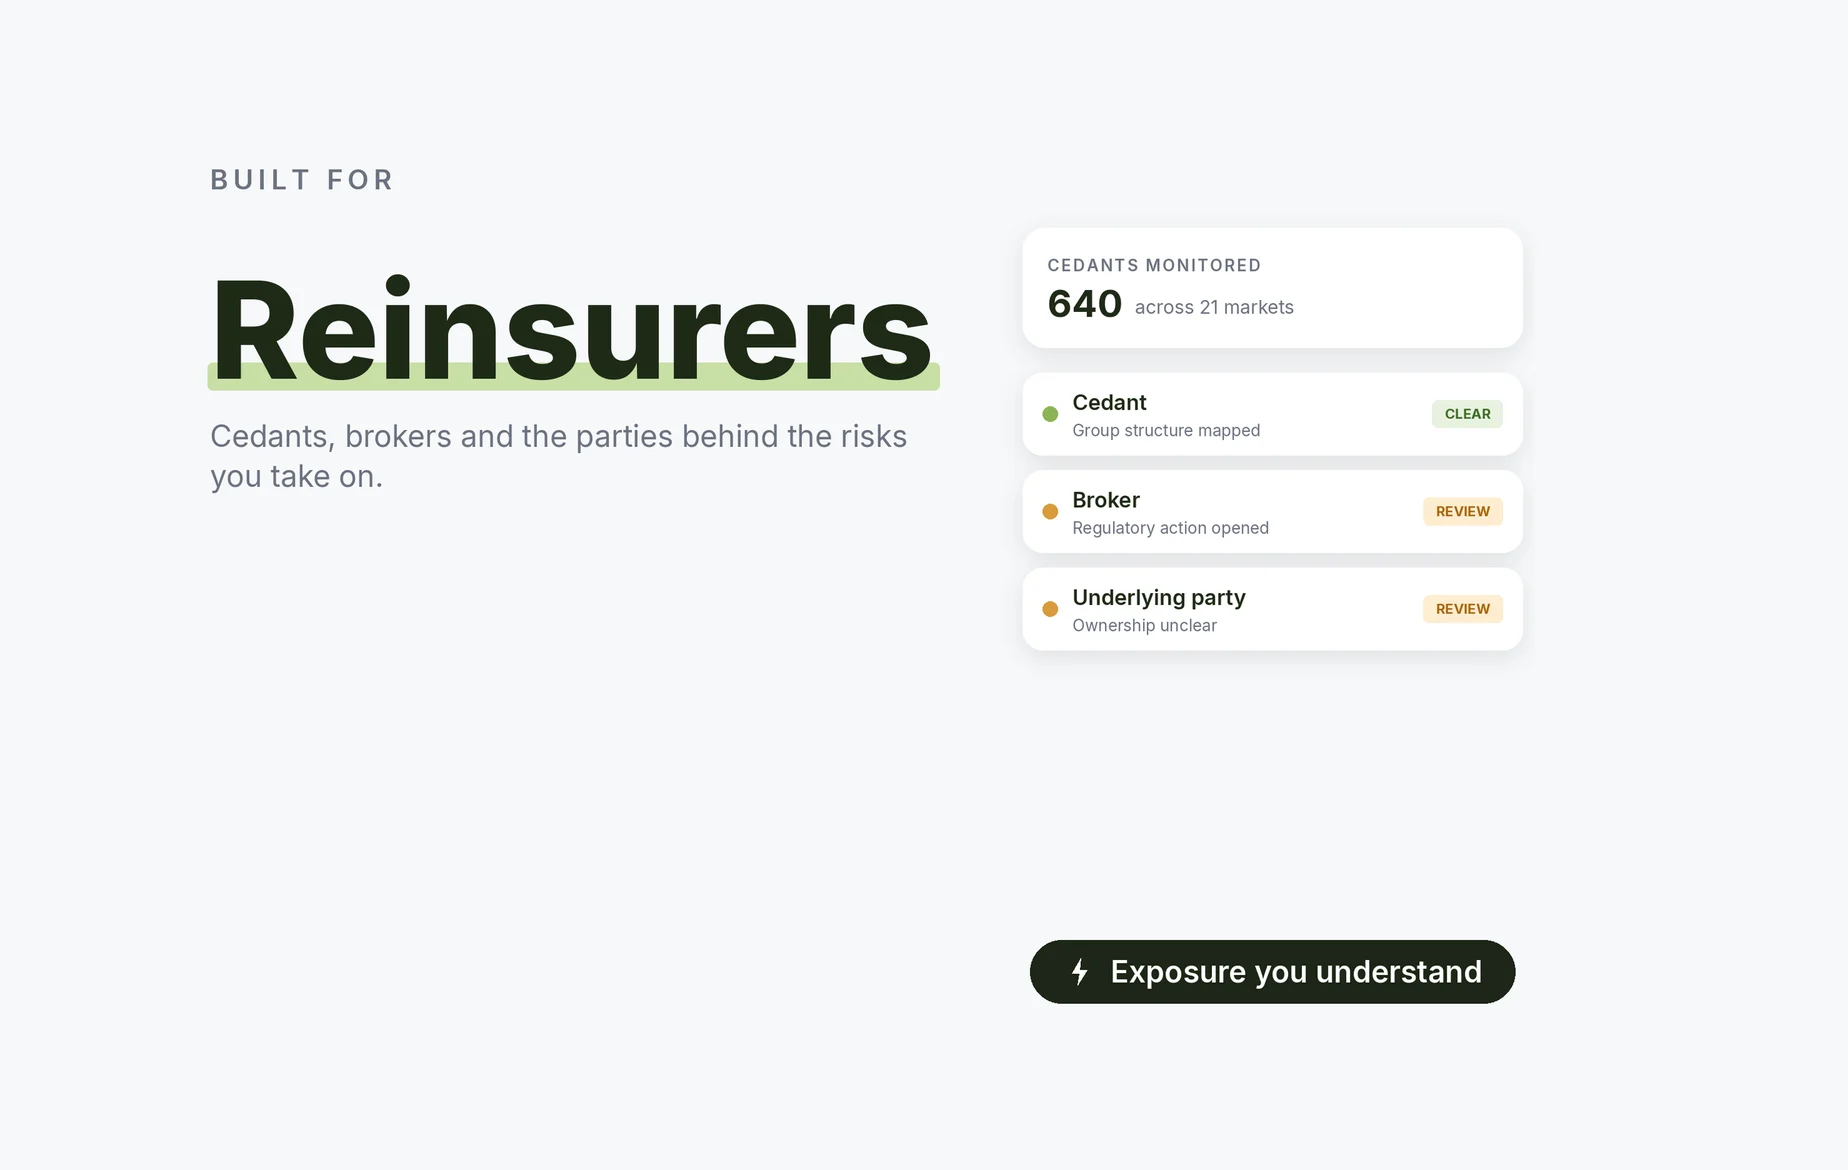
Beady for reinsurers: cedants, brokers and the parties behind the risks you take on
For Reinsurers
Screen cedants, brokers and the parties behind the risks you take on for sanctions and adverse media. The exposure you take on should be exposure you understand.
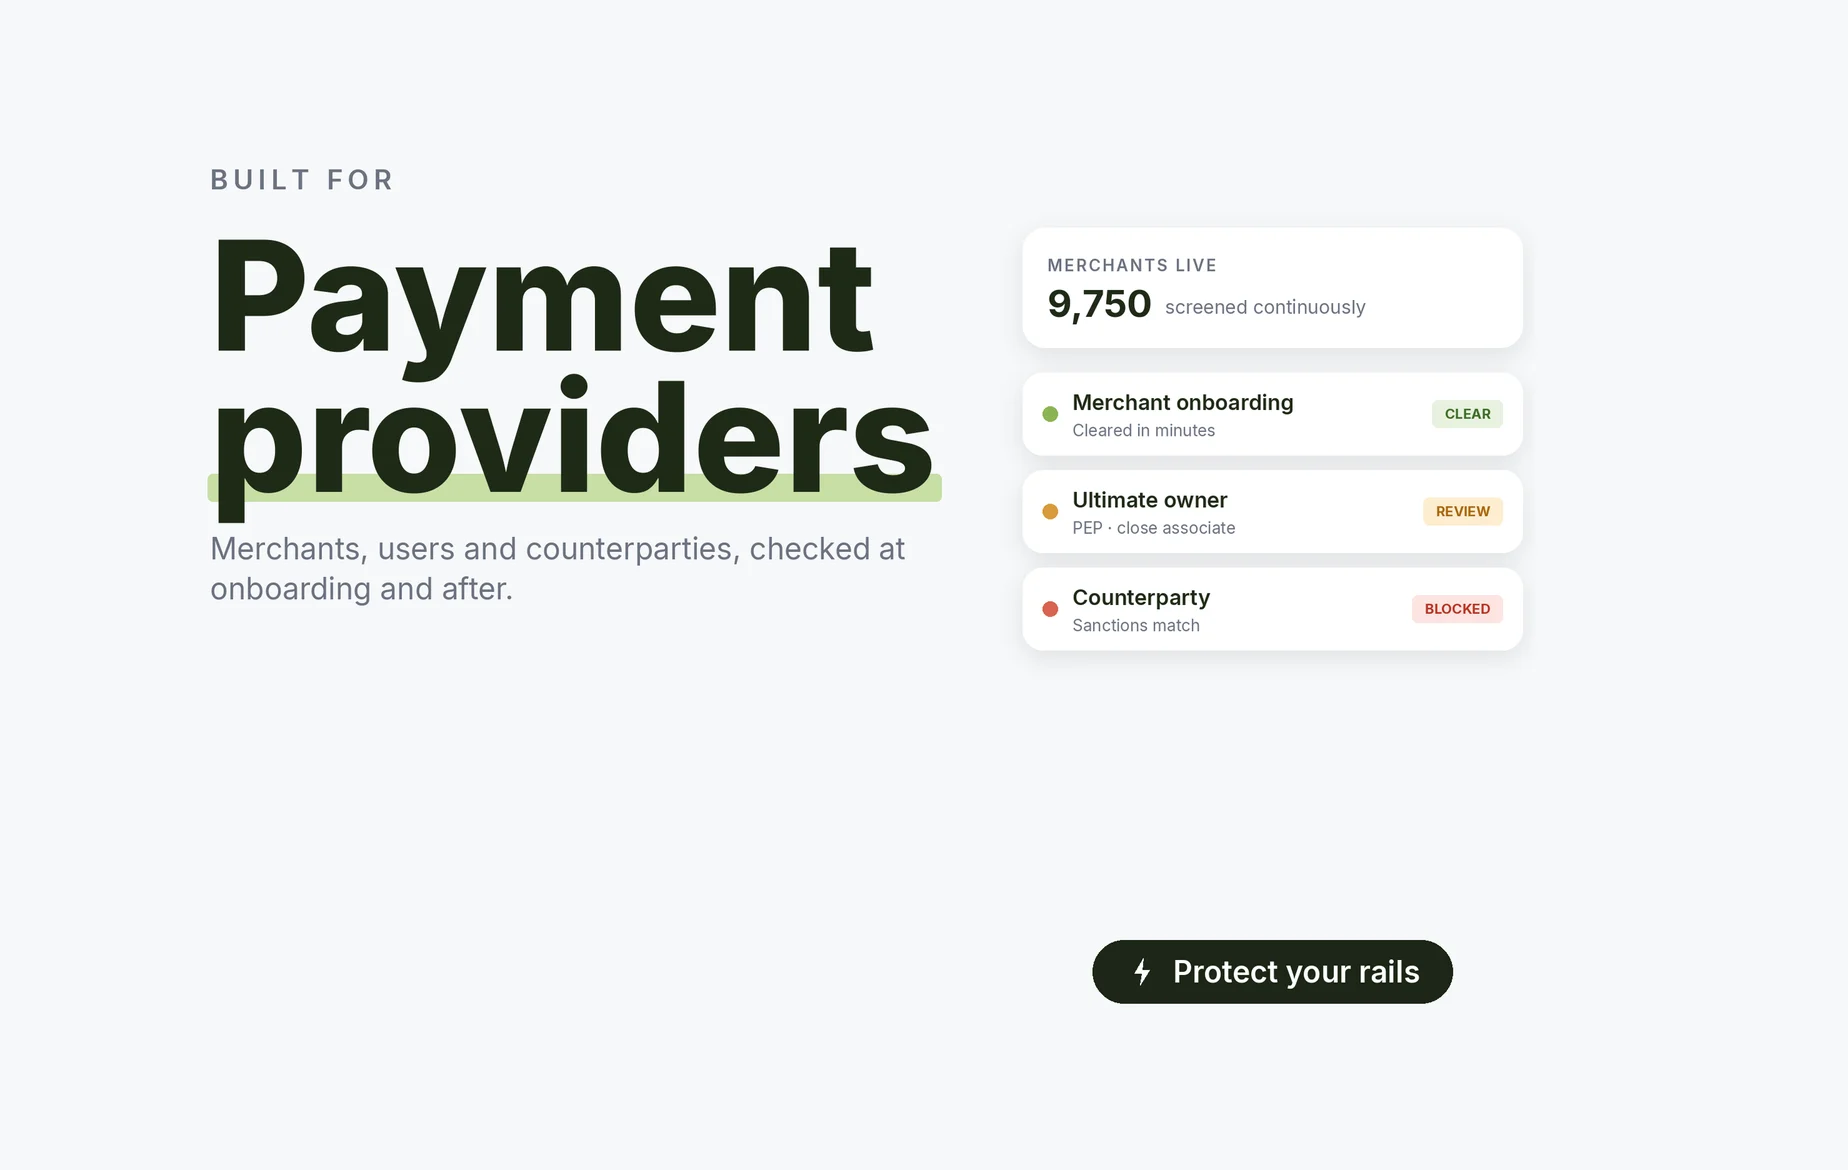
Beady for payment providers and EMIs: merchants, users and counterparties screened continuously
For Payment Providers and Stored Value Facilities
Screen merchants, users and counterparties for sanctions and adverse media risk at onboarding and every day after, and protect your payment rails and banking relationships.
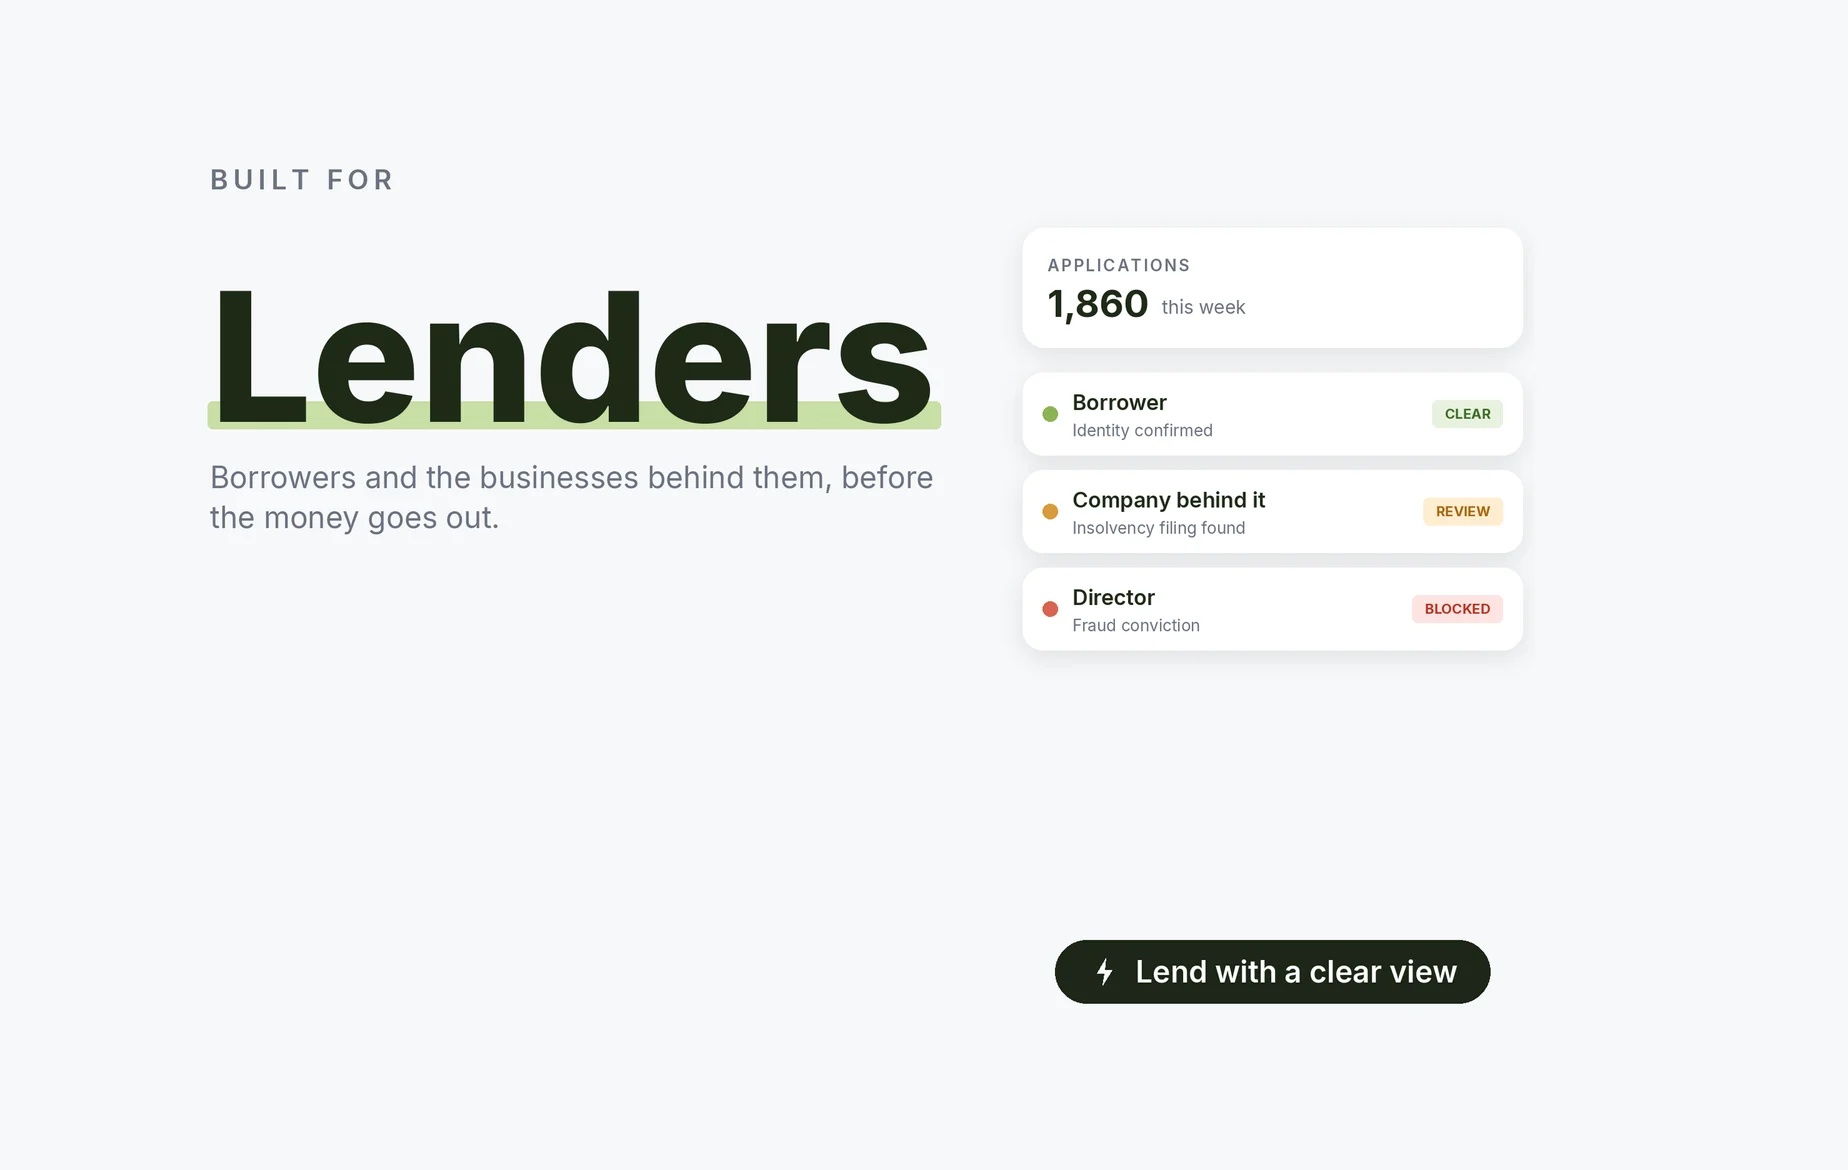
Beady for lenders: borrowers and the businesses behind them checked before the money goes out
For Lenders and Fintech Lenders
Screen borrowers and the businesses behind them for sanctions, bad press and fraud signals before you lend. Every application gets the same clear risk check.
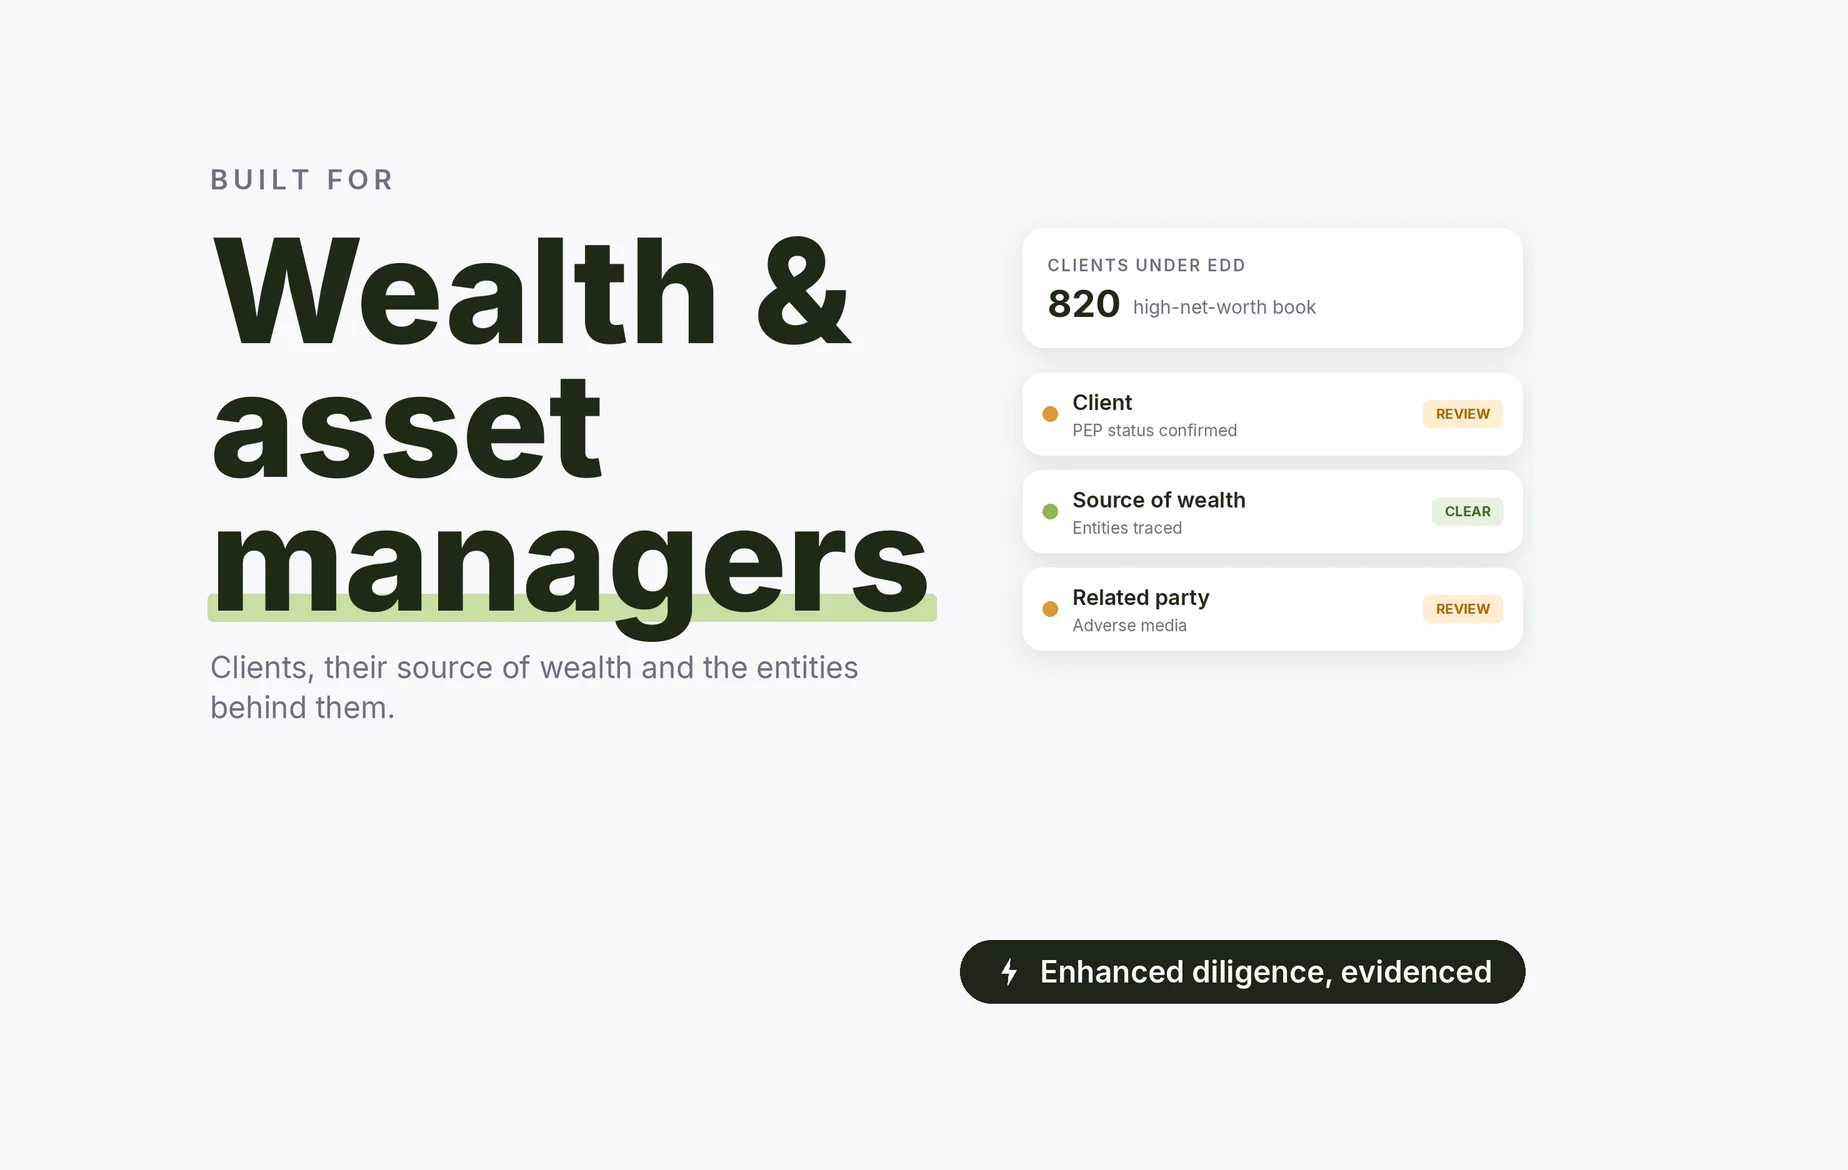
Beady for wealth and asset managers: clients, source of wealth and related entities under enhanced diligence
For Wealth and Asset Managers
Screen clients, their sources of wealth and the companies behind them for sanctions, PEP and adverse media. High-net-worth relationships, which are a big part of private banking in Dubai and Abu Dhabi, call for enhanced due diligence, and this helps you deliver it.
Beady for brokers and capital markets: counterparties and their owners checked pre-trade
For Brokers and Capital Markets
Screen counterparties, clients and the people behind them for sanctions and adverse media, so every trade or relationship starts with a clear view of who’s on the other side.
Beady for neobanks and fintechs: bank-grade screening at onboarding speed
For Neobanks and Fintechs
Screen customers and counterparties at scale and at speed for sanctions, PEP and adverse media, and build bank-level compliance into a fast-growing business from day one.

Built for the Regulators You Answer To

CBUAE (Central Bank of the UAE)
Meet the Central Bank’s AML, CFT and sanctions expectations for banks, exchange houses, finance companies, payment providers and insurers, with source-linked evidence for every check.
Support the financial crime controls the Dubai Financial Services Authority expects from banks, insurers, asset managers and other firms in the Dubai International Financial Centre.
Meet the AML and sanctions screening expectations of the Financial Services Regulatory Authority for firms licensed in Abu Dhabi Global Market.
Support the AML and due diligence obligations of brokers, investment managers and other securities firms supervised by the SCA.
Screen customers and counterparties to the standard Dubai’s Virtual Assets Regulatory Authority expects from virtual asset service providers.
Back up the suspicious transaction reports you file through goAML with documented, source-linked screening evidence.
Screen every party against the UAE Local Terrorist List and UN sanctions, refreshed daily, in line with the targeted financial sanctions rules overseen by the Executive Office for Control and Non-Proliferation. When a name is added, you can act without delay.
Screen against OFAC’s sanctions lists and keep the evidence US-facing partners expect. If you clear dollars or work with US correspondent banks, the standards set by FinCEN, the SEC, FINRA, the OCC, the Federal Reserve and the FDIC still reach you.
For groups with offices, clients or partners in the UK or Europe, screen against the warning lists and enforcement actions the FCA and PRA publish, and line up with EBA and ESMA standards on AML and market integrity.
If you also operate in Singapore, Australia or Canada, Beady supports the AML and CFT screening expected by MAS, AUSTRAC and FINTRAC.
Align with the FATF standards behind sanctions, PEP and beneficial ownership screening in more than 200 jurisdictions. Since the UAE left the FATF grey list in 2024, sticking to those standards is how firms here stay out of trouble.

Across Financial Services and Insurance

Financial services and insurance cover a lot of ground, and so does Beady. Screen and monitor the people and companies you deal with, whichever part of finance or insurance you work in.
Beady for retail banking: customers and account holders screened at onboarding and after
Retail Banking
Screen retail customers for sanctions, PEP and adverse media at onboarding and every day after, and meet AML obligations across thousands or millions of accounts.
Beady for commercial and corporate banking: corporate customers and groups with ownership mapped to people
Commercial and Corporate Banking
Screen corporate customers and map their ownership, checking the businesses and people behind them for sanctions, litigation and adverse media. Free zone and offshore structures included.
Beady for correspondent banking: both institutions screened before you clear through them
Correspondent Banking
Screen respondent banks and their counterparties for sanctions and adverse media risk, and keep the exposure that comes with correspondent relationships under control.
Beady for payments: merchants, users and counterparties screened before the money moves
Payments
Screen merchants, users and counterparties for sanctions and adverse media, and protect your payment rails and banking relationships.
Beady for lending and credit: borrowers and guarantors checked before the funds go out
Lending and Credit
Screen borrowers and the businesses behind them for sanctions, fraud and adverse media risk, and know who you’re lending to.
Beady for life insurance: policyholders and beneficiaries screened for sanctions and PEP at underwriting
Life Insurance
Screen policyholders, beneficiaries and the parties behind them for sanctions and adverse media, so you don’t write or pay out a policy for a high-risk party.
Beady for property and casualty insurance: claimants, agents and brokers with fraud signals surfaced before payout
P&C and General Insurance
Screen policyholders, claimants, agents and brokers for sanctions, fraud and adverse media risk, and catch problems at underwriting and at claims.
Beady for reinsurance: cedants and the risks behind them, exposure you can see
Reinsurance
Screen cedants, brokers and the parties behind the risks you take on for sanctions and adverse media. No blind spots in what you assume.
Beady for wealth and asset management: clients and source of wealth with enhanced diligence evidenced
Wealth and Asset Management
Screen clients, their sources of wealth and the companies linked to them for sanctions, PEP and adverse media, and meet enhanced due diligence requirements.
Beady for capital markets and trading: counterparty risk checked live before the desk trades
Capital Markets and Trading
Screen counterparties and the people behind them for sanctions and adverse media, so trading relationships start, and stay, with a clear view of the risk.
Beady for insurtech: digital onboarding at scale with bank-grade checks at API speed
Insurtech
Screen policyholders and partners at scale and at speed for sanctions, fraud and adverse media risk, and build compliance into a digital insurance model.
Beady for fintech and neobanks: customers screened at onboarding speed, compliance built in
Fintech and Neobanks
Screen customers and counterparties at scale for sanctions, PEP and adverse media, and reach bank-level compliance without a manual process.
Beady for pensions and funds: members, sponsors and managers in long relationships kept current
Pensions and Funds
Screen members, beneficiaries and the companies you deal with for sanctions and adverse media risk, and protect the funds and people you’re responsible for.

Set Once. Monitor Daily

For a financial institution, this isn’t optional. A thorough check at onboarding, then daily monitoring for every customer, counterparty and claimant. That’s what ongoing KYC is built on.

One-Time Screening

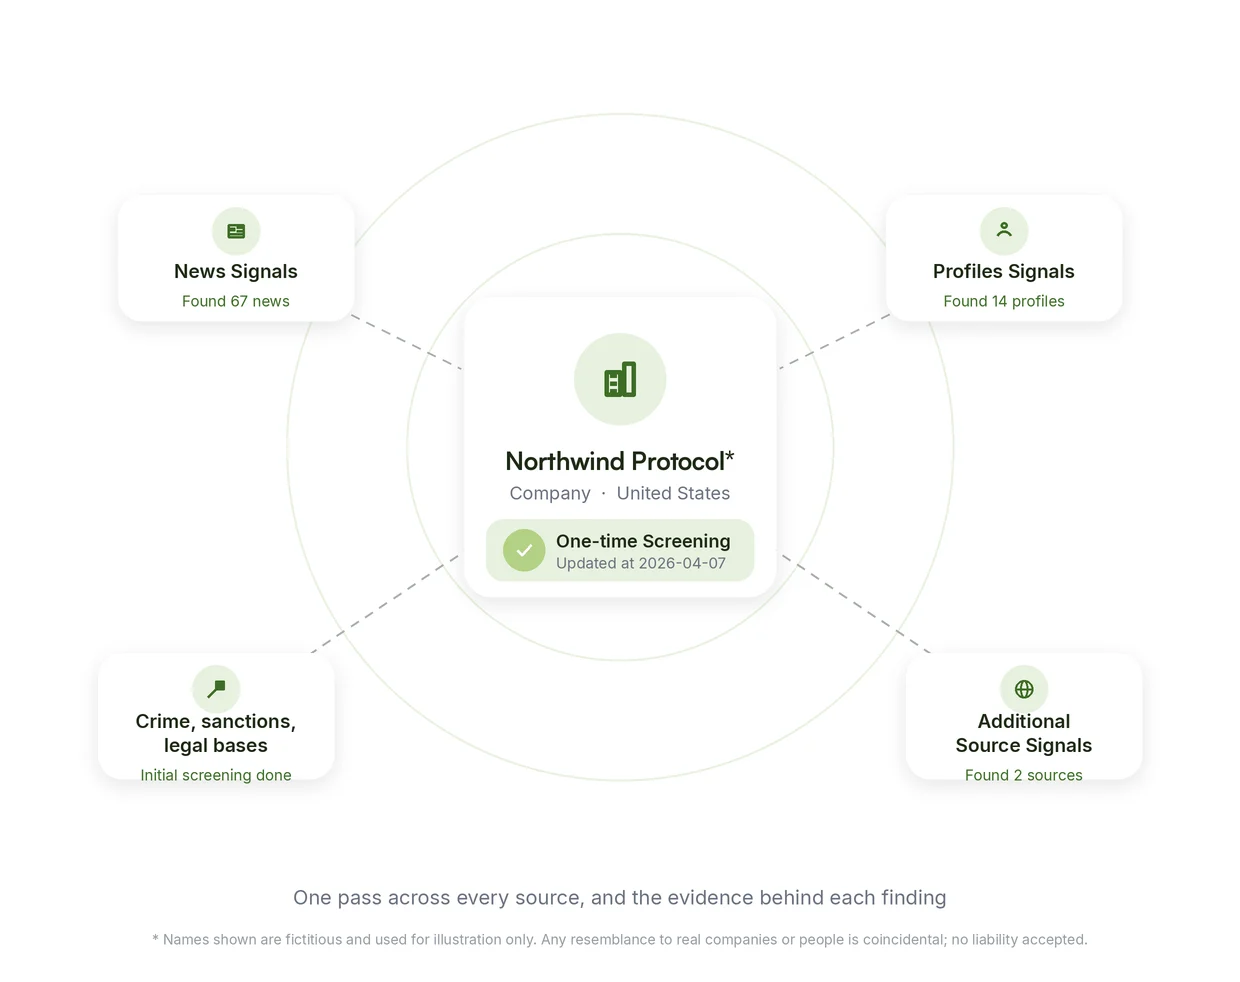
At onboarding, Beady runs a full check on a customer, company or claimant in one go: sanctions, PEP, criminal records, ownership and adverse media. No documents needed. It’s built around the decision you’re making right then, so you can approve a legitimate party quickly or catch a high-risk one before they’re on your books.

One-time scan of a name across news, profiles, legal bases and additional sources

Ongoing Monitoring

Once a customer is onboarded, the first check turns into ongoing coverage. Beady rescreens every customer and counterparty daily, so a new sanction, charge or scandal reaches you within hours rather than at the next periodic review. You screen once at onboarding, and your whole book stays under watch from then on, which is exactly what ongoing KYC asks for.

Ongoing Monitoring

Clear Intelligence, Built for Your Workflow

Every finding traced to its source, reports ready for audit, and results sent to the tools your team already uses.
Social Signals Monitoring
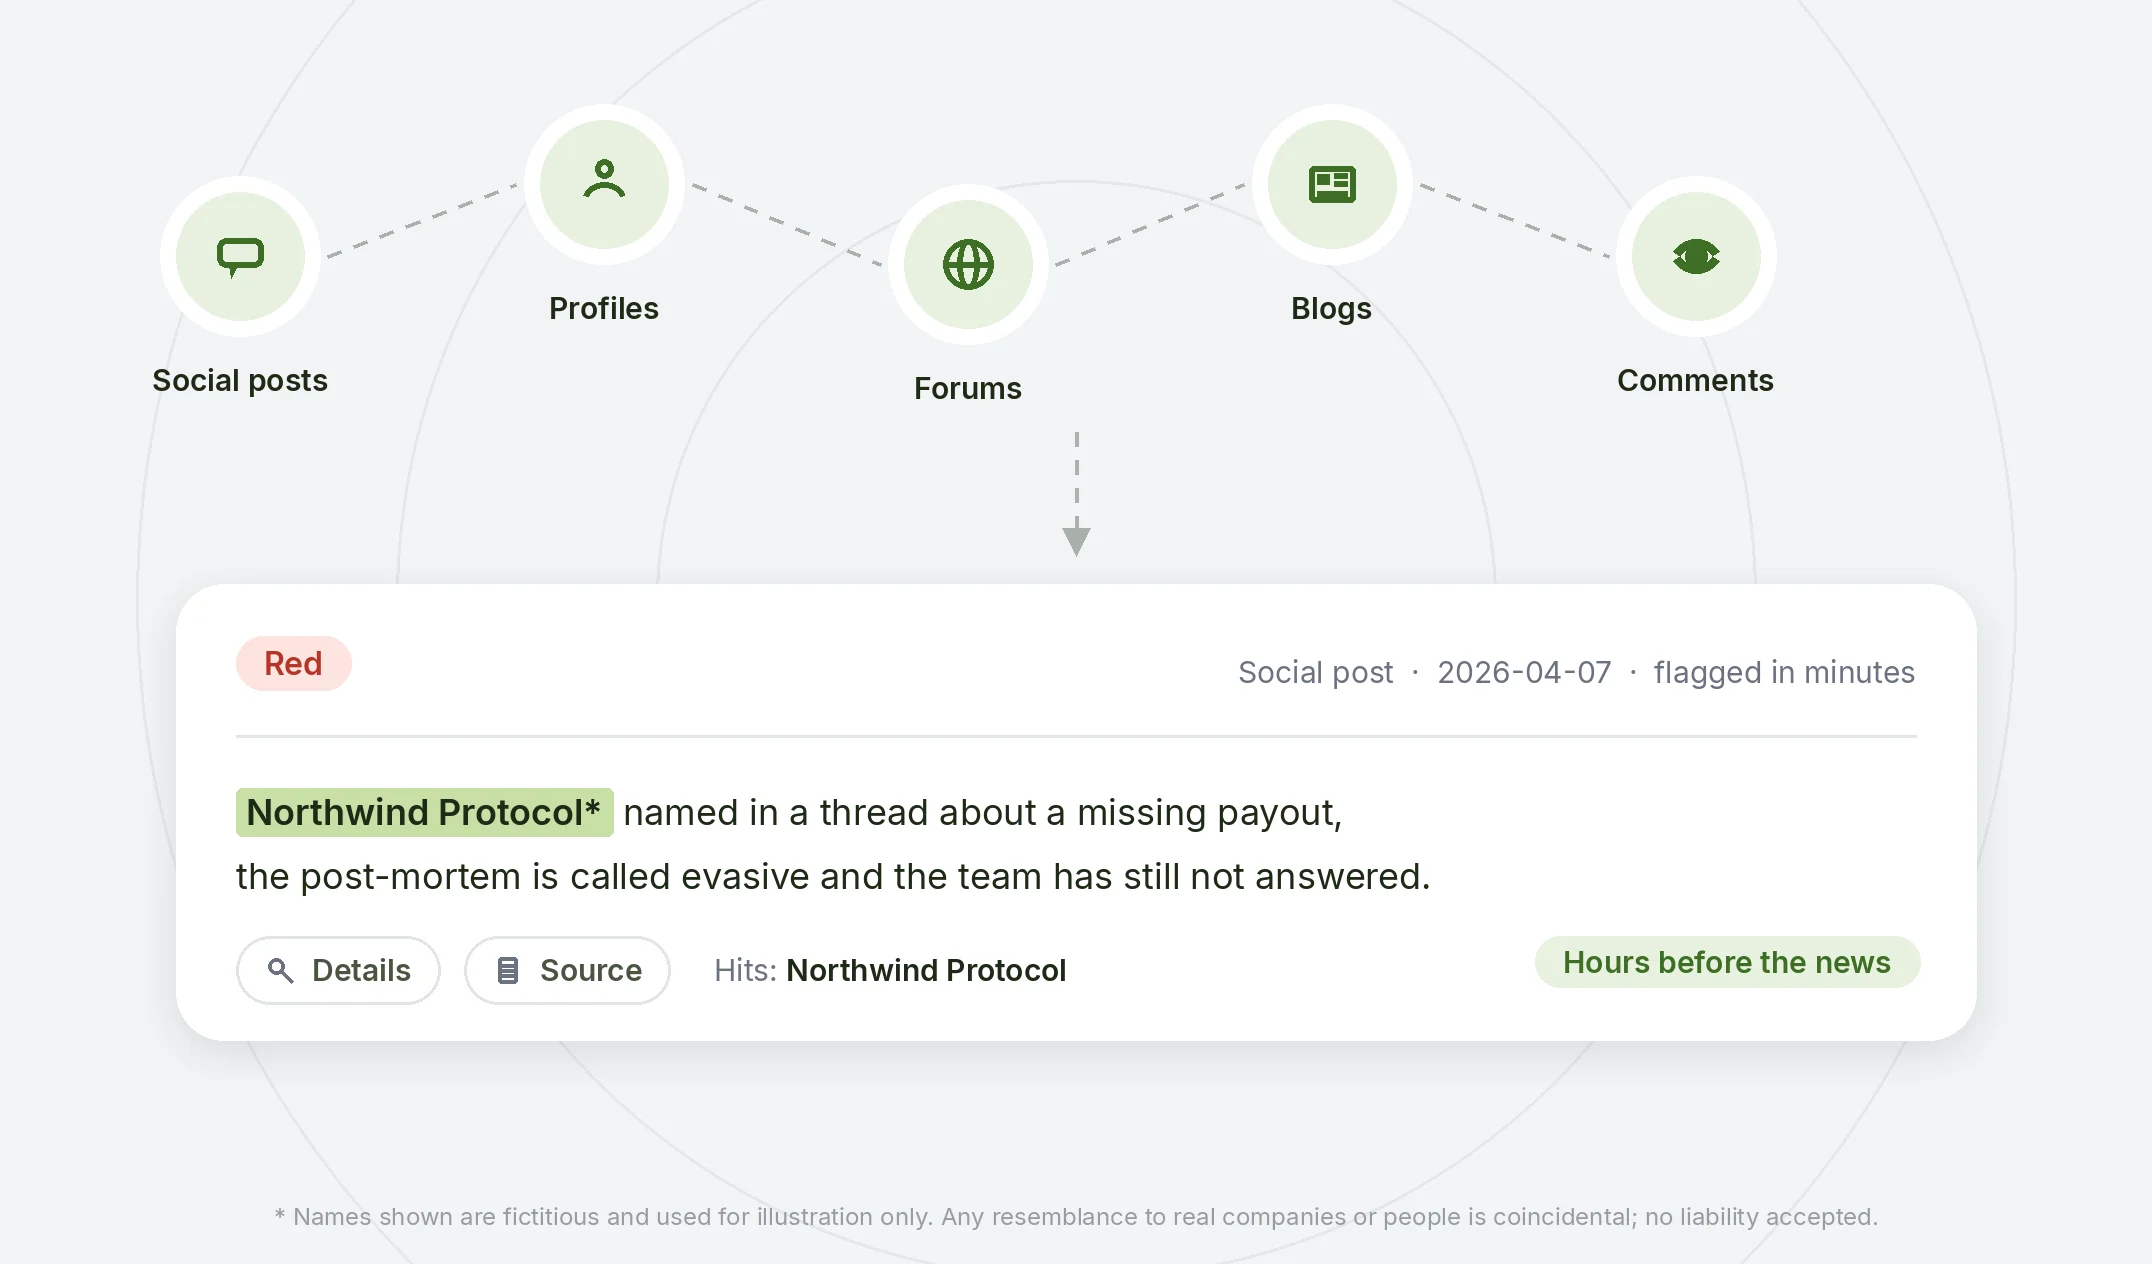
Beady also follows public social media in real time. A fraud accusation, an arrest or the first signs of a scandal often appear there hours or days before the news or any official record.

How early varies by party and sector, but it covers everyone you screen. You’ll hear about it as early as anyone can.
Social Signals Monitoring
Messenger Integration for Daily Risk Alerts
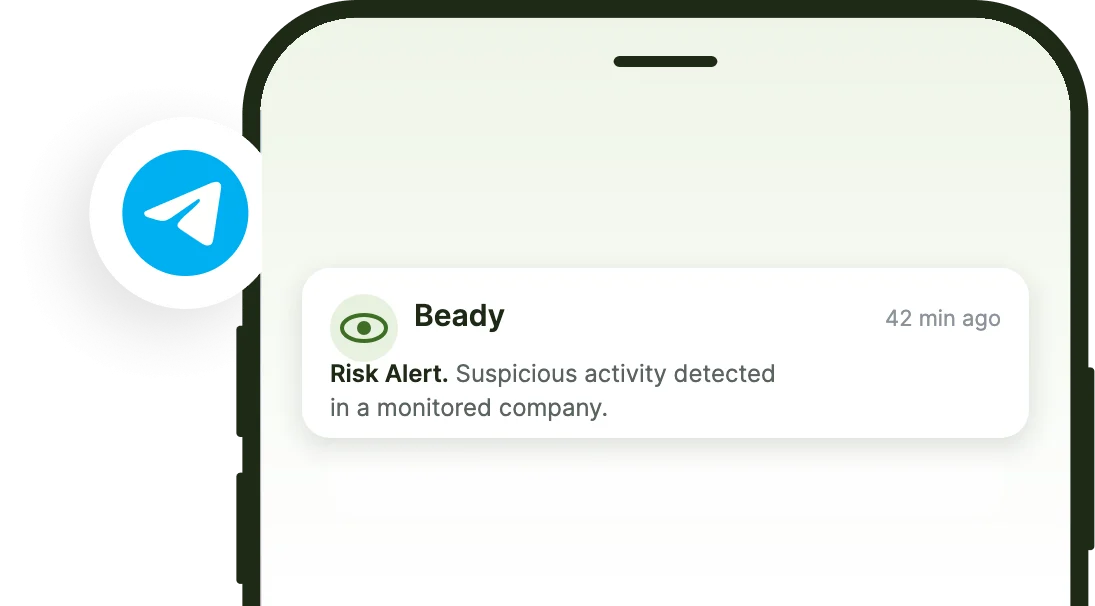
Beady can send daily alerts to Telegram and other messaging apps with the biggest changes across your customers and counterparties. No need to log in every day.

Glance at the summary on your phone, and log in when you want the full report and the evidence.
Messenger Integration for Daily Risk Alerts
Quality of the Data Provided
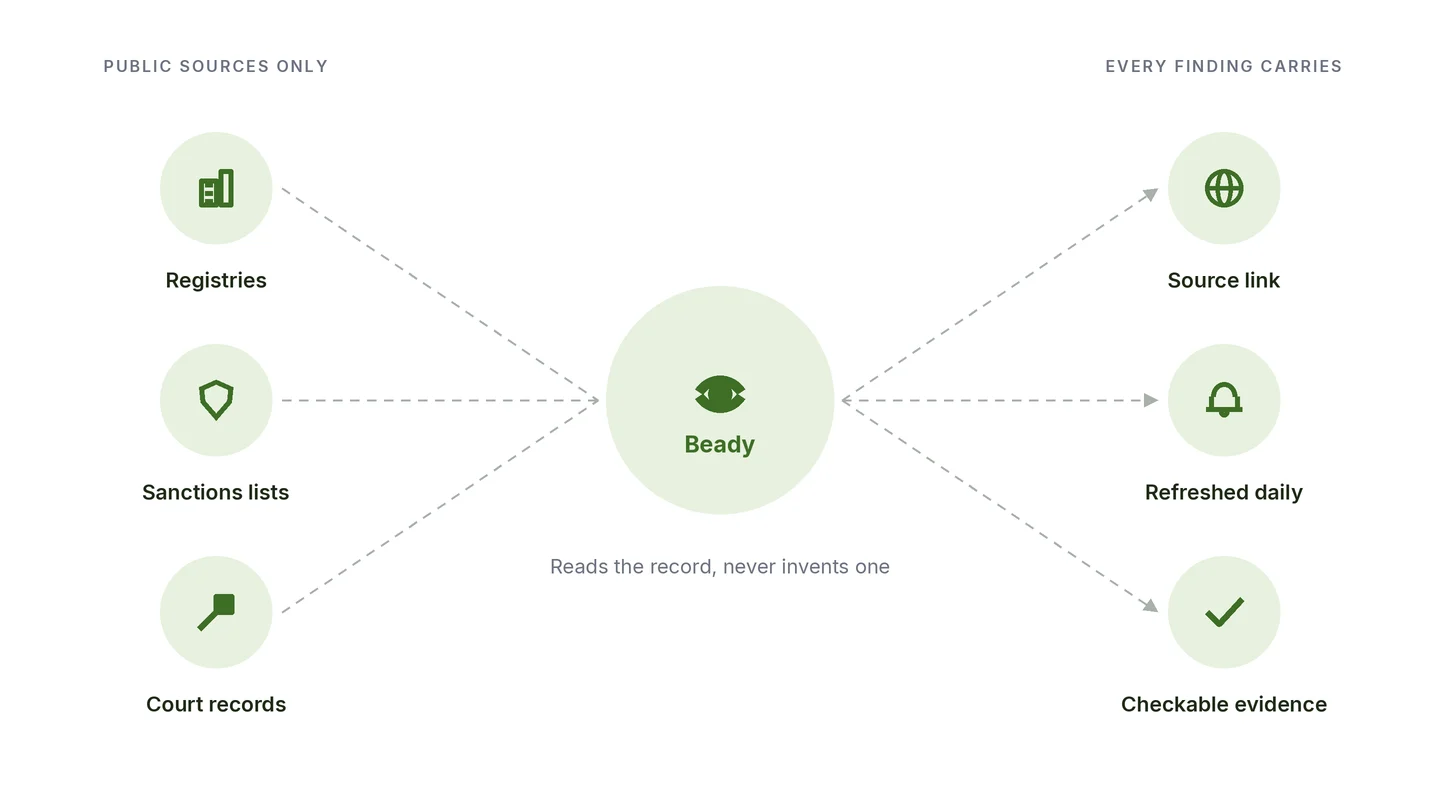
Beady only uses publicly available data. It’s refreshed daily and updated as soon as something changes, and every finding links to the record it came from.

The AI doesn’t make things up. You can check any result against its source, so your compliance decisions stand up.
Quality of the Data Provided
Report Consolidation
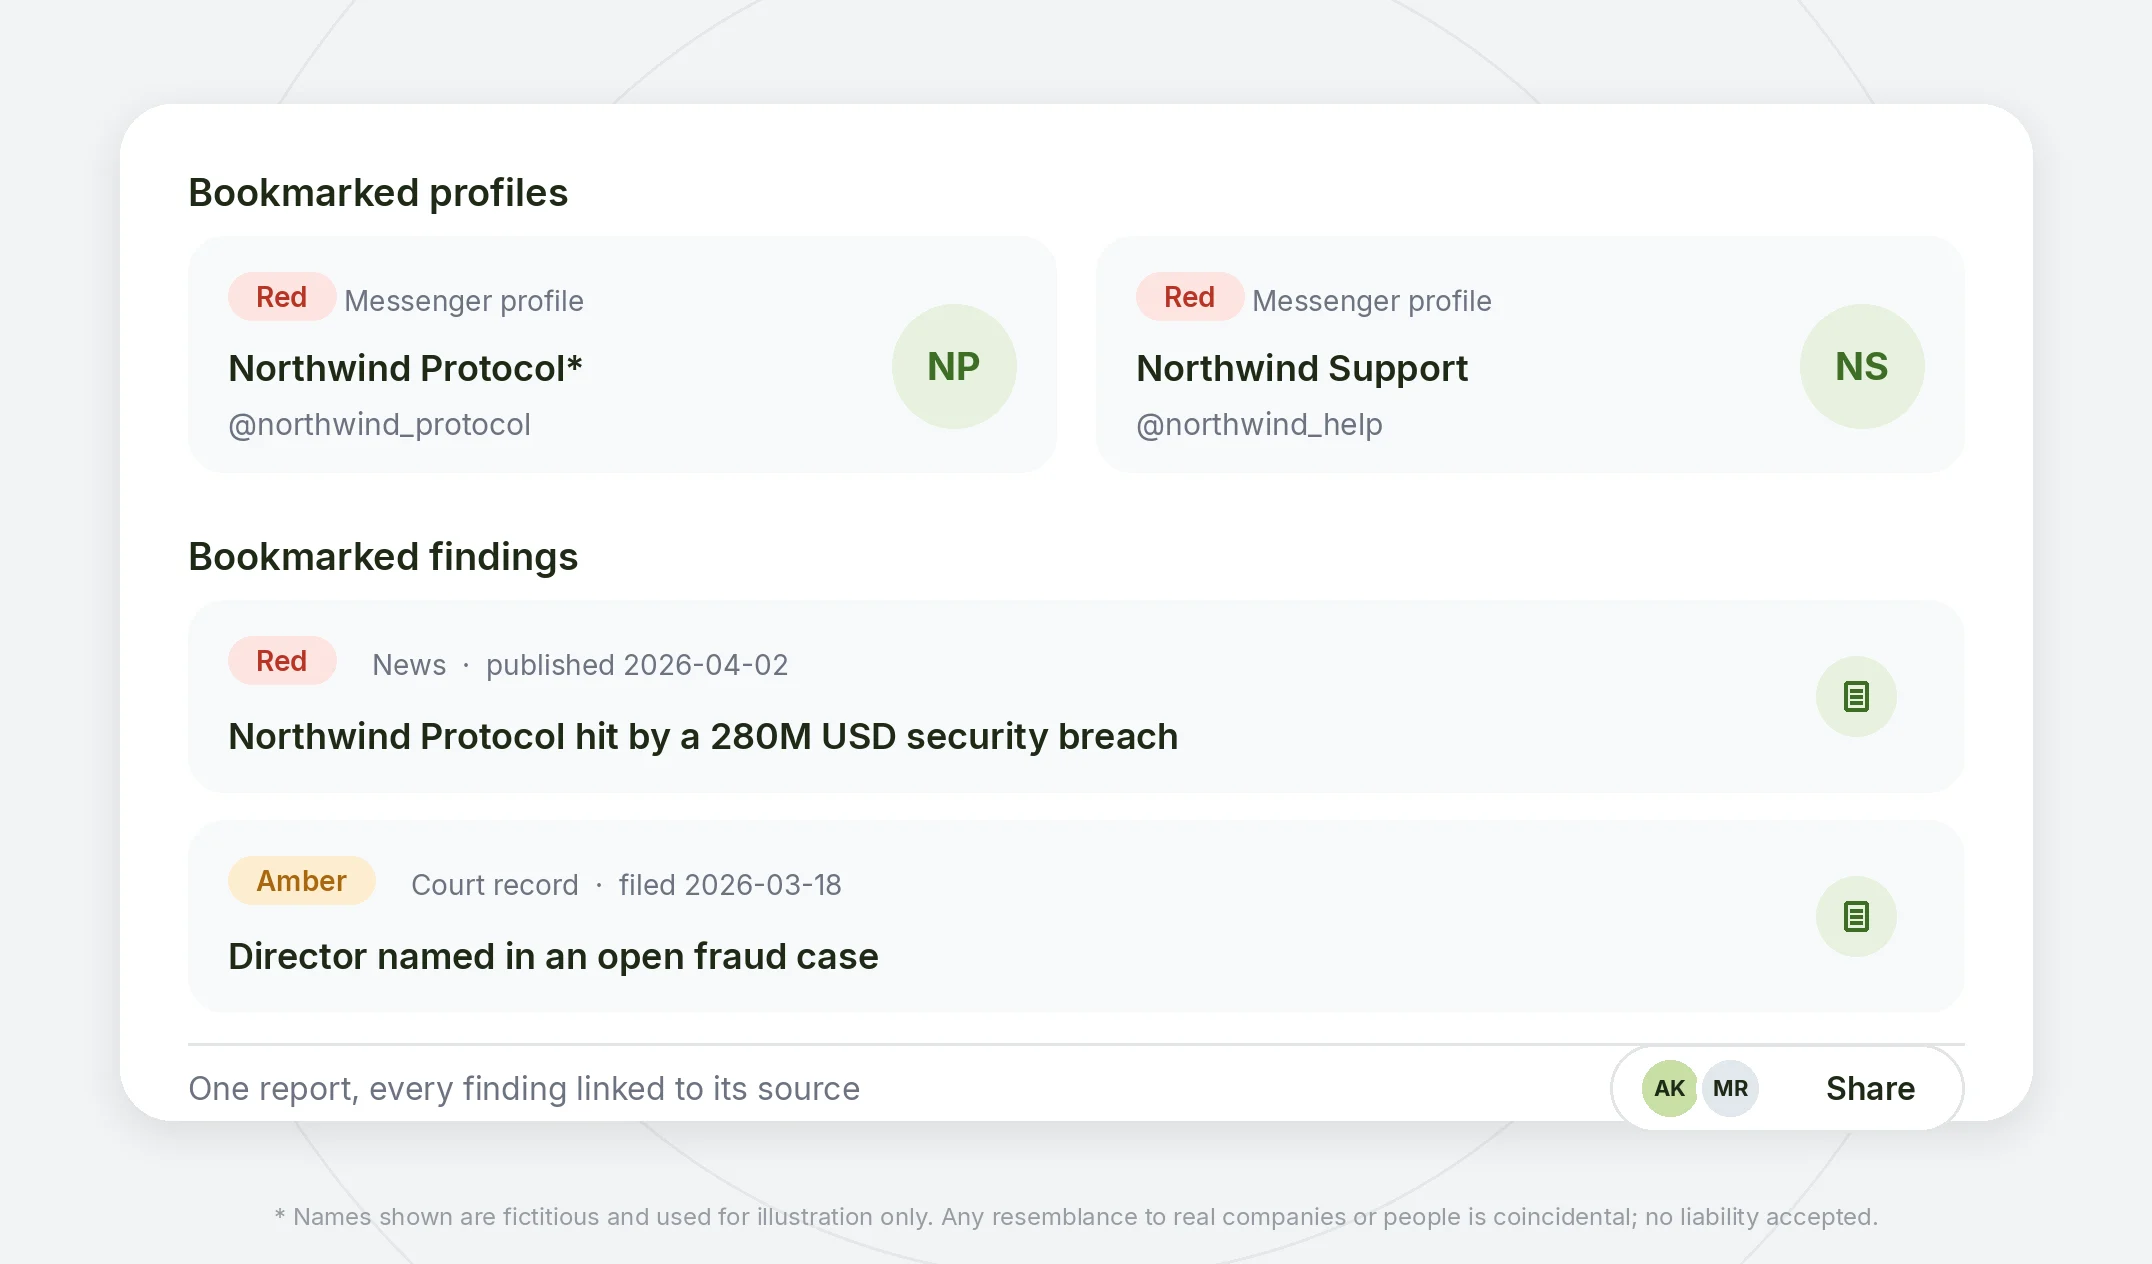
Bookmark the findings you need and build a report around a customer, a counterparty or a case. Sharing it with your compliance team, your MLRO, an auditor or a regulator takes a couple of clicks.

Everyone works from the same findings, so nobody has to rebuild the picture by hand.
Report Consolidation

How It Works

From a name to a verified risk profile, and then to daily monitoring. Here’s how it goes.
Add the Party
Step 1
Add the Customer or Entity
Type in the customer, company or claimant you want to check. No documents needed.
Screen
Step 2
Screen
Beady checks the name against sanctions, PEP, criminal, adverse media and ownership data, plus more than 100,000 other sources, all in one go.
Map and Filter
Step 3
Map and Filter
The AI maps the ownership, throws out noise and false matches, and keeps only what actually applies.
Build the Profile
Step 4
Build the Report
What’s confirmed goes into one audit-ready profile, sorted by severity, with a source for every finding.
Monitor and Share
Step 5
Monitor and Share
Add the party to daily monitoring and share the report with your compliance team, auditors or regulators whenever you like.

Ready to get started?

You can be live in 24 hours instead of weeks.

Frequently Asked Questions

What does Beady do for a financial institution or insurer?
Beady screens the people and companies you deal with, including customers, counterparties, policyholders, claimants, agents and partners, against sanctions, PEP, criminal, litigation and adverse media sources. It maps their ownership across more than 200M entities and keeps monitoring them. It’s how you meet your AML, KYC and KYB obligations and stay ahead of the sanctions and fraud risks UAE regulators hold you to.
Beady supports the screening and monitoring obligations behind most financial regulators. In the UAE that means the CBUAE, the DFSA in DIFC, the FSRA in ADGM, the SCA and VARA, along with the UAE Local Terrorist List rules and reporting to the UAE FIU through goAML. For firms with international links, it also covers the expectations of the FCA and PRA in the UK, the SEC, FINRA, FinCEN, OCC, Federal Reserve and FDIC in the US, the EBA and ESMA in the EU, and MAS, AUSTRAC and FINTRAC elsewhere, all built on FATF standards. It runs the sanctions, PEP, adverse media and ownership checks these rules require, screens the enforcement actions and warning lists these bodies publish, and keeps source-linked evidence of every check. Beady is an independent tool and isn’t affiliated with or endorsed by any regulator.
Beady handles the screening at the heart of AML: KYC checks on individuals and KYB checks on companies, run against sanctions, PEP, adverse media and ownership data in minutes. It filters out the noise, links every finding to its source and keeps monitoring after onboarding. You meet your obligations at onboarding, stay compliant afterwards and have the evidence to show it.
Yes. After the first check at onboarding, Beady rescreens every customer and counterparty every day, so a new sanction, charge or scandal reaches you within hours instead of at the next periodic review. That kind of continuous coverage is exactly what ongoing (or perpetual) KYC means, and you can get alerts in the platform or on Telegram.
Instead of relying on simple name matching, Beady’s AI looks at context, follows ownership links and weighs how credible each source is before deciding what’s relevant. Up to 95% of the noise falls away: matches on the wrong person, old flags, coverage that was positive in the first place. Your compliance team ends up with a short list of real hits rather than an endless pile of false positives.
Yes. Beady screens policyholders, claimants and everyone around a claim against sanctions, criminal, litigation and adverse media sources, and picks up the fraud signals and red flags that point to a high-risk or fraudulent claim. Your team can investigate before the claim is paid, not chase it afterwards.
Sanctions carry some of the heaviest penalties in finance. Beady screens every customer, counterparty and claimant against the main sanctions lists, including the UAE Local Terrorist List, the UN, OFAC, the EU and the UK’s HMT, all refreshed daily. A newly sanctioned party is caught the day they’re listed, and every match links to its source, ready for your records and your regulators.
Most checks come back in a few seconds. Bigger ones might take a minute or two. Either way, it runs by itself. Beady goes through every source, works out who owns what, throws away the noise and gives you one clean profile at the end. That speed changes what you can do. You can screen a customer while they’re still onboarding and they won’t notice the wait. And a corporate client that would have kept an analyst busy for hours takes a fraction of the time.
More than 100,000 public sources. That includes sanctions lists such as the UAE Local Terrorist List, the UN, OFAC, the EU and UK HMT, plus PEP databases. Beady also covers international most-wanted and criminal registries, regulatory and enforcement lists, and adverse media from more than 100,000 news sources. On top of that, there are corporate registries covering more than 200 million entities and officers, and public social media. Everything is refreshed daily.
Keyword alerts throw mentions at you and leave you to sort them out. Beady was built for risk. Its AI checks that a hit is really about your customer, judges how relevant it is, clears out up to 95% of the noise and brings in sanctions, ownership, litigation and criminal data alongside the news, all with sources. You get verified risk information, not an unfiltered feed.
Trusted by compliance and risk teams at